Top-rated property appraisers.

Best property appraisers near Ola, AR

Enter your zip and get matched with up to 5 pros

Need a pro for your property appraisal project in Ola, AR?

Select your specific project to find the pro for you.

Top-Rated Property appraisers in Ola - Updated Nov 2026

Avatar for Cravens Appraisal, LLC
Cravens Appraisal, LLC
5.0(
4
)
Appraisal - Real Estate

Serving Ola, AR and surrounding areas

In business since 2016

Free estimates

Emergency services offered

At Cravens Appraisal, LLC, we specialize in providing professional real estate valuation services. Appraisal reports are prepared with the precision that the industry demands. All of our assignments comply with the Uniform Standards of Professional Appraisal Practice. We appraise all types of residential properties: single family, acreages, condominiums, 2-4 family investment properties, vacant lots and high-end lakefront dwellings. With over 10 years of appraisal experience, (7 years real estate appraisals & 3 years title insurance underwriting) serving the Arkansas River Valley area, Cravens Appraisal, LLC, has built its business on integrity, honesty and accuracy! Lastly, we are fully capable of providing Spanish speaking services and reports. Call us today for your free estimate!

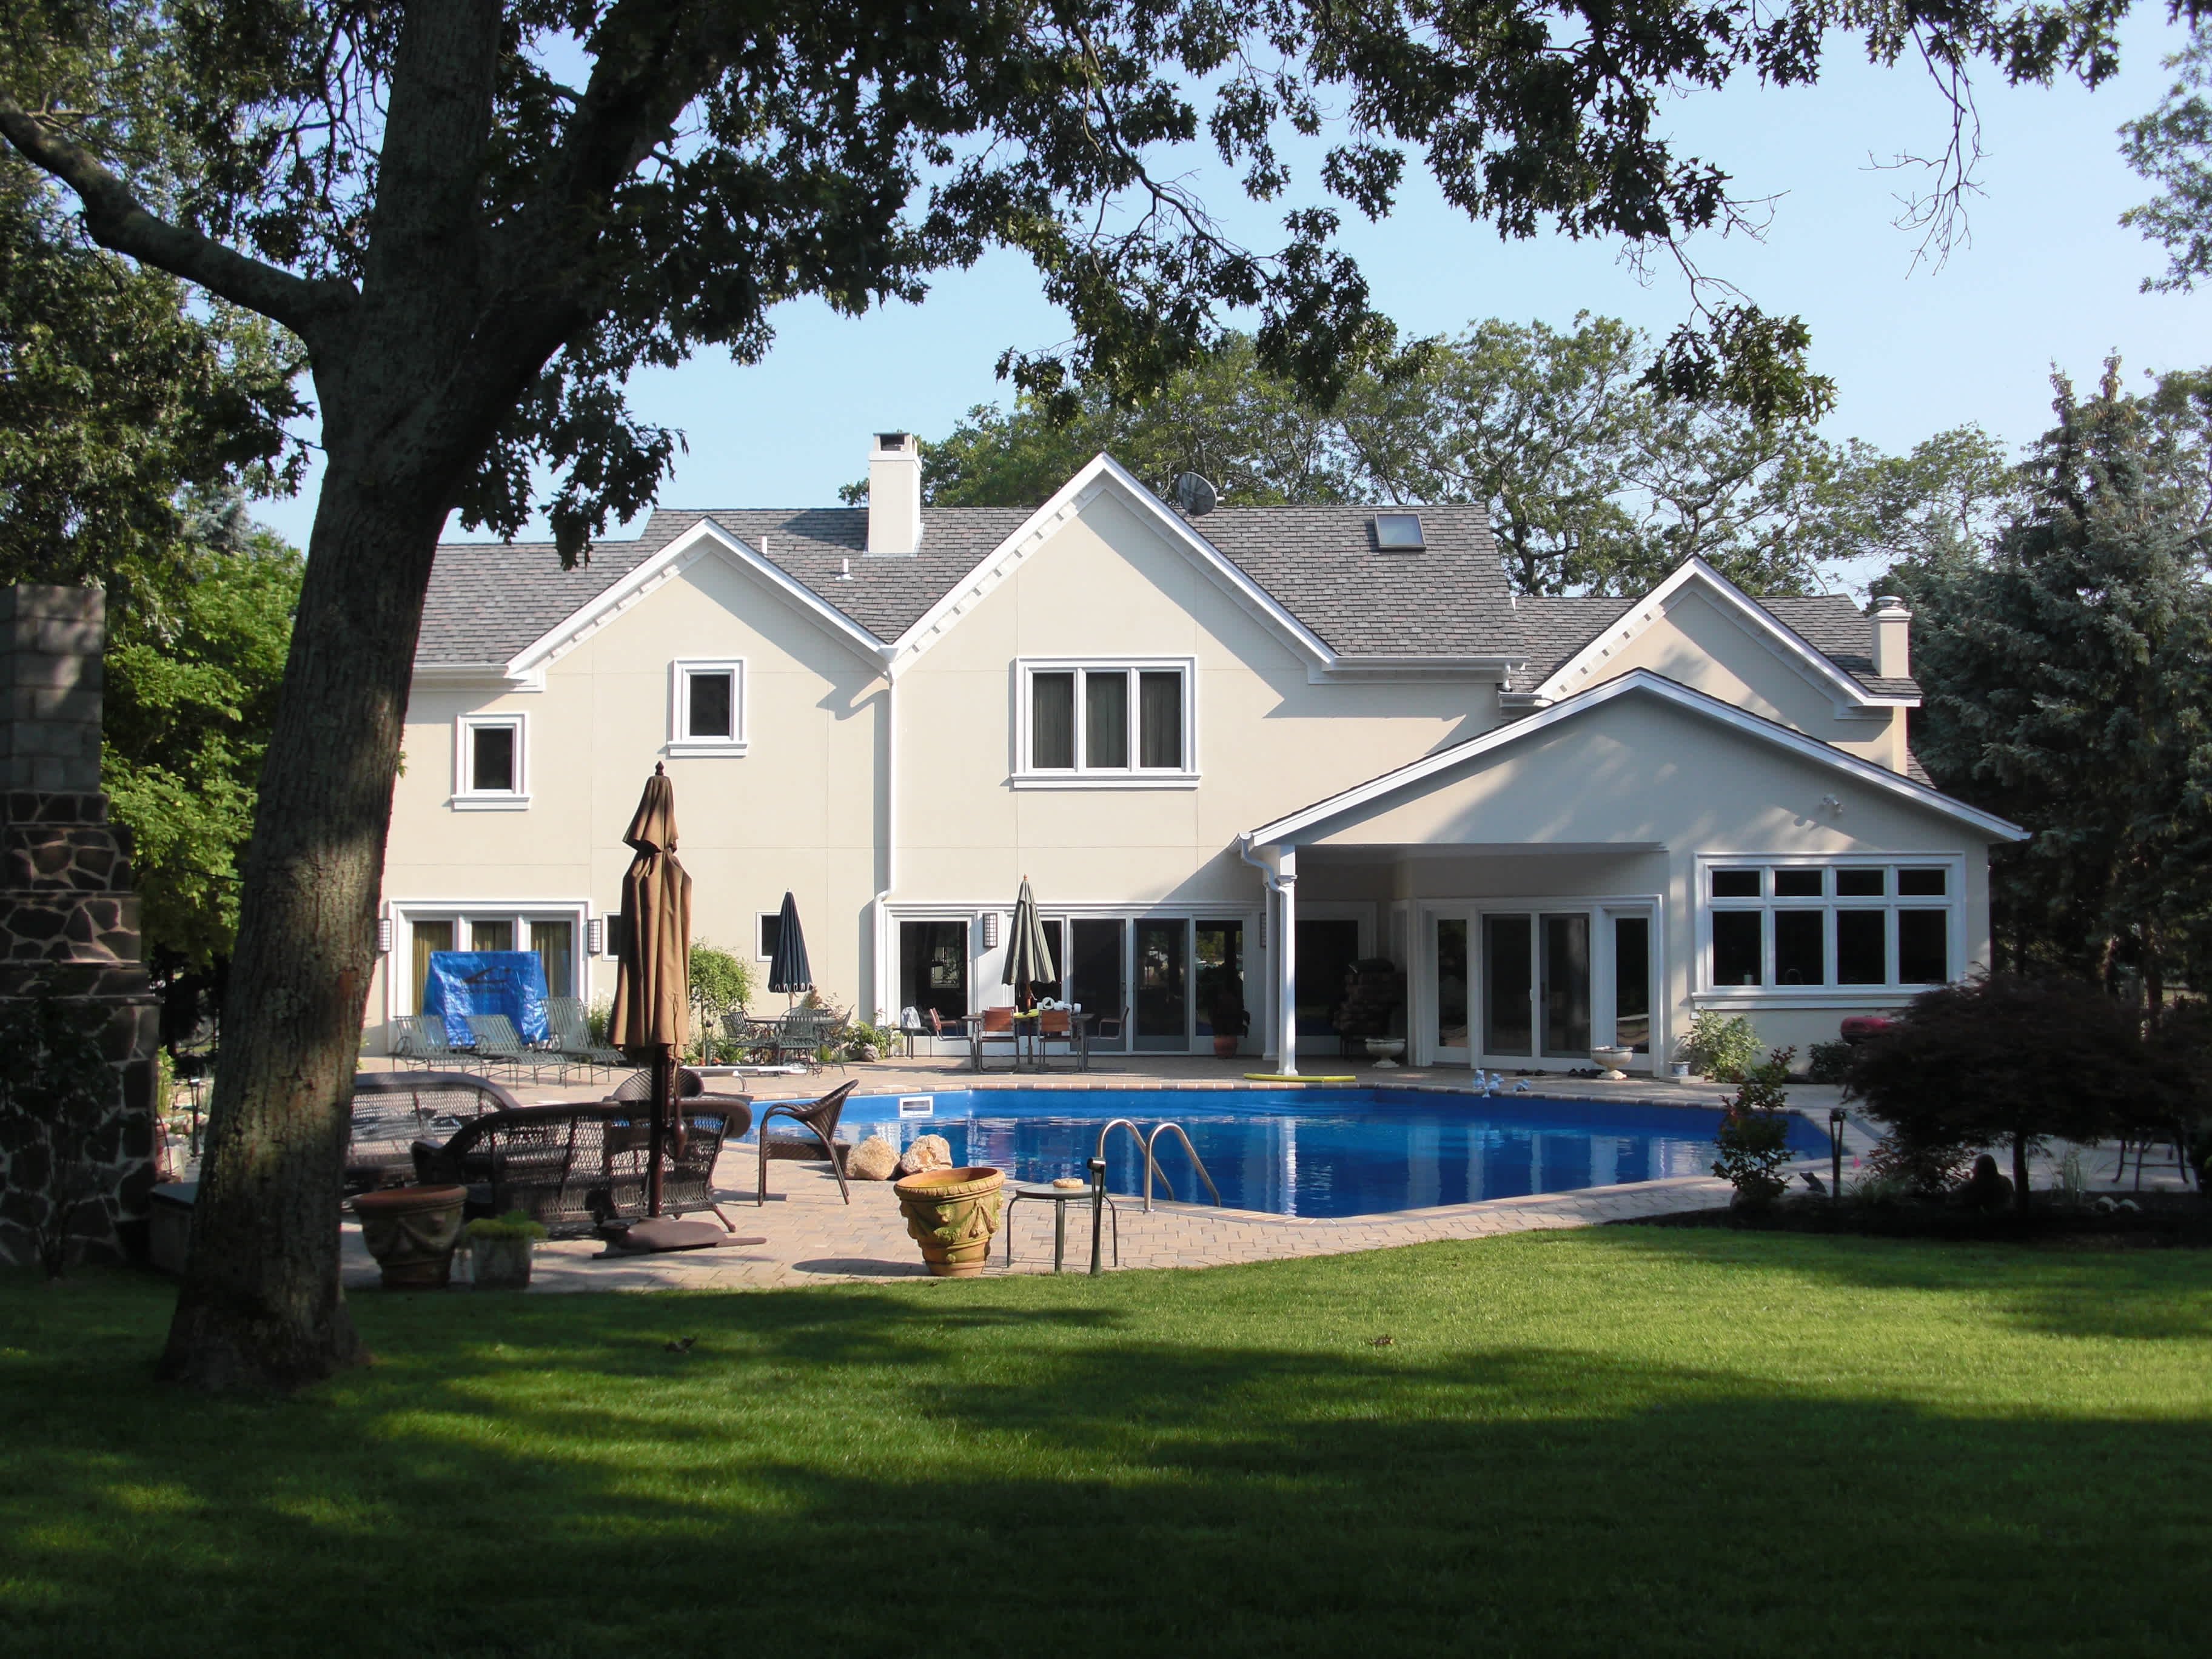
Large Home in Alma w/ Multiple Shops
Rear Exterior
Large Deck & Yard
Alma New Construction
Response time3 days
Recommended by100%of homeowners
Home Base Appraisal Management
New to Angi
Appraisal - Real Estate

Serving Ola, AR and surrounding areas

In business since 2013

Free estimates

Credit card accepted

Home Base Appraisal Management was founded in May 2009. We started our company with high hopes in the front room of the owner's home. We took everything one step at a time and have achieved more than we ever thought we would. After 6 years in business, we have grown out of the basement and have become one of INC 5000's fastest growing companies in America. Home Base Appraisal Management has a reputation of outstanding communications and customer service. We have one of the nations largest networks of appraisers and provide appraisal services in the majority of the United States. Please call us today to book your appointment!

Response time4 days
Property Appraiser FAQs, answered by experts

While a finished basement adds value to your home, it is assigned a different value than space on the main floors. An appraiser will assess the square footage of a finished basement at about 50% to 60% of the value of the square footage for the rest of your home. Appraisal value for a finished basement depends on your location’s real estate market and the specifics of the basement and how it was finished. 

While there’s technically no limit to the dollar amount you can borrow for a home addition, the standard limit is around 80% of the value the addition is expected to add to your home. That means you could feasibly borrow up to $80,000 if an appraiser determines that the addition or bump out will add $100,000 in value to your property. You might also be limited by your debt-to-income ratio or credit score.

The differences between market value and appraised value depend on the local market, so they can match, or either one can be higher than the other. In a “seller’s market,” where there is an abundance of buyers, market value will likely sit higher than the appraised value because there’s more demand for the low inventory of homes. In a “buyer’s market,” where there are more homes than there are buyers, the market value is more likely to sit below the appraised value to entice buyers.

Appraisals can come in above or below the list price or offer price for a property, and where it falls depends on many factors. Those include the condition of the property, the location, and the age of the home, but often, the condition of the market is the biggest determining factor. Where demand is high for properties, buyers compete with each other for homes, which tends to drive up offer prices above where appraisals come in. Where demand is low, you’ll often see the opposite happening.

Both conventional loans and FHA loans are types of mortgages, but they have a few key differences. Conventional loans are backed by private lenders without any government backing, and FHA loans are guaranteed by a government agency. FHA loans are designed to be easier for borrowers with low credit scores or income to qualify for.

The Ola, AR homeowners’ guide to property appraisals

From average costs to expert advice, get all the answers you need to get your job done.