
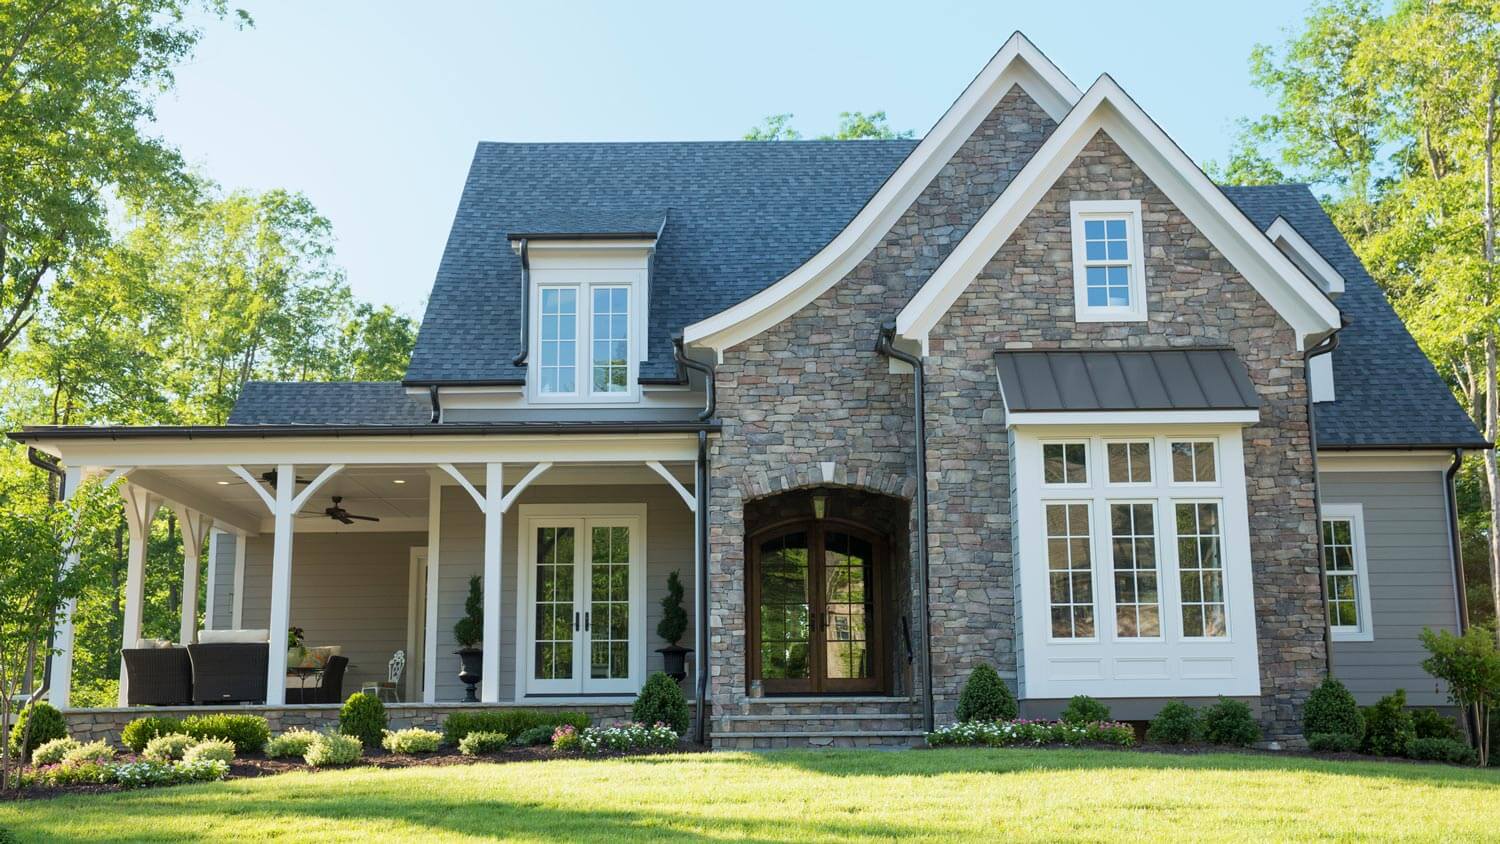
Insuring your home protects you financially and satisfies your mortgage. Learn how much homeowners insurance could cost you.
Unpack all the details about homeowners insurance here


Homeowners insurance protects your home's structure, possessions, and provides liability coverage if you cause injury or property damage to others.
Expect to pay around $1,200 per year for homeowners insurance on a $250,000 home, giving you financial protection and peace of mind.
Review your policy every two years and update coverage after home improvements, expensive purchases, or getting new pets to keep your protection current.
Hiring a local home warranty company helps you understand coverage gaps and ensures you have the right protection for floods, earthquakes, and maintenance requirements.
Homeowners insurance is that one thing everyone needs but no one thinks about—until your spouse forgets about the casserole in the oven. But don’t wait until an emergency to learn what’s in your homeowners insurance plan. After all, it covers your house and possessions, and it may provide financial protection if you're found liable for causing injury or property damage to someone else.
It’s not always easy to understand, but it’s important you do to make sure if the unthinkable happens, you’re covered. So let’s make the topic a little less intimidating and go over six tips to ensure you fully understand your insurance.
Homeowners insurance is an insurance policy that covers both the structure of a home and its possessions. So if a homeowner lost both their house and their possessions in a catastrophic event like a fire, they would file a homeowners insurance claim, and the insurer would send them a check for the amount covered.
“Based on the principle of indemnity, the homeowner would receive compensation for such a loss at the rate equal to the cost of the loss plus inflation,” says Asya Biddle, Angi Expert Review Board member and manager of The Dust Busters janitorial company in Williamsport, PA.
Depending on your coverage, it may also protect you financially in case of any liability for injuries or property damage to others caused by you or members of your family (even pets).

Here’s a short list of what homeowners insurance typically covers:
Structure: The insurance will cover the main structure of your home and any attached structures, like a porch. It’ll also cover other structures on your property, like a shed.
Possessions: The insurance will cover valuable possessions in the home, such as electronics or jewelry.
Liability: The insurance will protect you financially if you cause injury or property damage to someone else.
Living expenses: If the catastrophic event forces you to move off the property and into a hotel, the insurance can help with paying temporary living expenses while the home is being repaired.
"Every provider breaks down the coverage differently. While some providers may cover such possessions in their homeowners' policies completely, others may cover it up to a maximum cost, while others will not cover the cost without an endorsement added for specific possessions,” says Biddle.
Many homeowners are unpleasantly surprised to find that homeowners insurance doesn't cover everything. For example, these policies often don't provide coverage in the case of floods or earthquakes. In those cases, homeowners often have to purchase separate policies covering those types of catastrophic events. Generally, you'll want to get these additional policies if you're in an area prone to these types of disasters.
Also, if you aren't properly maintaining your home, homeowners insurance won't cover incidents caused by poor maintenance. For example, if you haven't been maintaining your roof and it starts leaking into your home and causing water damage, insurance may not cover that.
Your claim may also be denied if you don't do a good enough job documenting the damage for a homeowners insurance claim.
The average annual homeowners insurance premium is $1,200 per year, or about $100 per month for a home that’s worth about $250,000. As you can see, it's a pretty low-cost service that can provide you with tremendous peace of mind.
The amount of coverage you need depends on your situation, but be very careful to ensure you have the right amount of coverage. Don't sign up for any homeowners insurance policy and think you're fully covered.
Ask yourself a few questions:
Do you need flood insurance?
What about coverage for earthquakes?
What does the policy require of you as a homeowner in terms of maintenance?
Will they deny a claim if you don't do certain things, like if you go away for the winter on vacation and fail to take measures to ensure your pipes don't freeze?
Determine what you need coverage for, and then read through your policy carefully to ensure it's all covered. If not, ask your insurer to add that coverage or reach out to another insurer.
Also, ensure the amount of money you’ll receive if something happens is adequate. A common homeowners insurance myth is that insurance policies always fully compensate the homeowner for the value of the covered items. Many insurance policies cap coverage, so if your house burns down in a fire, you may not get enough money to replace it.
Your homeowners insurance policy should feel like a safety net, so ensure that you’re regularly updating your coverage at least every two years for the most up-to-date deal.
Update your coverage whenever you make home improvements or even purchase expensive items, like jewelry, electronics, and appliances. This is especially true if you live in an area susceptible to earthquakes, floods, and other weather-related issues. Even getting a new pet can affect your policy, particularly for certain dog breeds that are required to be on your homeowners insurance policy.
Our home is a testament to Custom Paint Jobs LLCs skill and dedication. Simply the best!
 Custom Paint Jobs, LLC
We needed windows in our home, and we couldnt believe we got our entire home done for under $14,000. We have a lot of windows, and not only was it affordable, but it got done in a timely manner! Thanks guys, I truly appreciate you all!
 Window Depot USA of Central Ohio
Working with Mike on our first home purchase was an absolute pleasure. Mike put us at ease and made the process of buying a home fun. Mike is knowledgeable, honest, professional, and punctual. He worked with our busy schedule and always made time for us. When a home came on the market that...
 Michael Marshall - Buyer's Resource Realty Svcs.
Mary cleaning service does an amazing job cleaning my home. They go over and beyond the cleaning services that I have had in the past. They are very punctual and thorough with cleaning my home, I’m extremely happy with the service they provide and I highly recommend them.
Clint was and is very Professional and takes pride in this company and his work. Definitely recommended him to everyone in my hi-rise building. Excellent proposal and no hidden charges or surprises. Don't find that in today's world.
 Footprints Floors of Columbus
From average costs to expert advice, get all the answers you need to get your job done.
Insuring your home protects you financially and satisfies your mortgage. Learn how much homeowners insurance could cost you.
If you’re not sure if you want moving insurance, you’re not alone. Most people don’t. This guide helps you learn the reasons you need or don’t need the coverage.
When you buy a home, you’ll likely need hazard insurance to protect it from things like natural disasters and burglaries. Learn how insurance costs can vary.
“Will a new roof lower my homeowner's insurance?” Find out the answer to this common question in our guide.
Homeowners insurance is a boon in the face of water damage, but it doesn’t cover everything. Learn about the sudden and unexpected damages it does cover.
Find out if homeowners insurance will cover slab leak repair if a crack in your slab foundation is causing water damage at your home.