
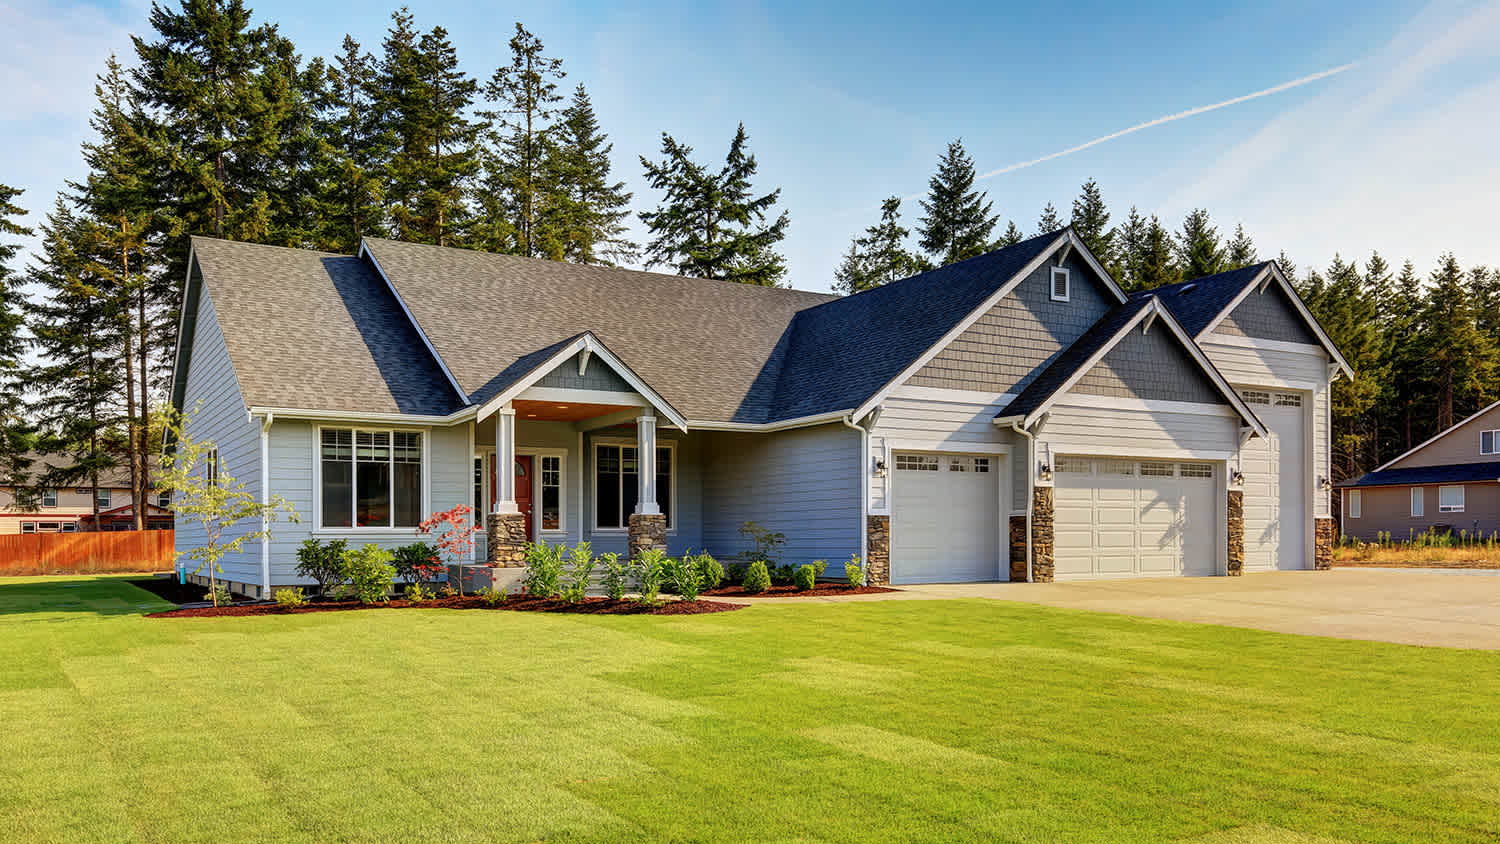
When you buy a home, you’ll likely need hazard insurance to protect it from things like natural disasters and burglaries. Learn how insurance costs can vary.
Real estate service costs depend on your project and location. Check with a local pro for your specific job.

Homeowners insurance premiums run $645 to $2,148 a year based on your home’s value, averaging $1,500.
Your state’s weather risks and insurance laws shape premiums, so disaster-prone areas cost more than mild climates.
You should budget for separate flood or earthquake coverage in high-risk zones, since standard homeowners insurance excludes them.
Hiring a local real estate agent helps you find competitive insurance rates and ensures your coverage protects your home investment.
In 2026, the national average cost of homeowners insurance is $1,500 per year. Most homeowners pay between $900 and $1,800 annually, with the cost driven by your home's value, your state's weather risks, and the coverage limits you choose.
The cost of homeowners insurance depends heavily on the state you live in, since each state carries its own insurance laws and weather risks. The table below shows how annual premiums vary by state:
| State | Average Cost in 2026 |
|---|---|
| Alabama | $1,578 |
| Alaska | $1,000 |
| Arizona | $1,600 |
| Arkansas | $2,100 |
| California | $1,088 |
| Colorado | $1,488 |
| Connecticut | $1,200 |
| Delaware | $800 |
| Florida | $1,744 |
| Georgia | $1,370 |
| Hawaii | $862 |
| Idaho | $1,350 |
| Illinois | $1,350 |
| Indiana | $1,200 |
| Iowa | $1,192 |
| Kansas | $2,800 |
| Kentucky | $1,800 |
| Louisiana | $2,000 |
| Maine | $1,000 |
| Maryland | $1,200 |
| Massachusetts | $1,269 |
| Michigan | $1,300 |
| Minnesota | $1,900 |
| Mississippi | $2,150 |
| Missouri | $1,950 |
| Montana | $1,750 |
| Nebraska | $1,865 |
| New Mexico | $1,087 |
| Nevada | $850 |
| New Hampshire | $850 |
| New Jersey | $1,000 |
| New Mexico | $1,450 |
| New York | $1,085 |
| North Carolina | $1,400 |
| North Dakota | $1,900 |
| Ohio | $1,200 |
| Oklahoma | $3,150 |
| Oregon | $800 |
| Pennsylvania | $950 |
| Rhode Island | $1,250 |
| South Carolina | $1,335 |
| South Dakota | $1,900 |
| Tennessee | $1,900 |
| Texas | $2,400 |
| Utah | $750 |
| Vermont | $850 |
| Virginia | $1,050 |
| Washington | $950 |
| Washington, D.C. | $900 |
| West Virginia | $1,050 |
| Wisconsin | $928 |
| Wyoming | $1,200 |
Your home's estimated value, also called dwelling coverage, is one of the primary drivers of your annual homeowners insurance premium, with annual costs from $645 to $2,150. What you'll pay varies significantly depending on how much your home is worth, as shown in the breakdown below:
| Estimated Home Value | Annual Average Cost in 2026 |
|---|---|
| $49,999 and under | $645 |
| $50,000–$74,999 | $748 |
| $75,000–$99,999 | $826 |
| $100,000–$124,999 | $888 |
| $125,000–$149,999 | $937 |
| $150,000–$174,999 | $981 |
| $175,000–$199,999 | $1,018 |
| $200,000–$299,999 | $1,114 |
| $300,000–$399,999 | $1,272 |
| $400,000–$499,999 | $1,482 |
| $500,000 and above | $2,148 |

Many variables shape your home insurance premium, from your home's age and materials to your neighborhood's risk profile and your own claims history. Understanding the most common cost factors helps you anticipate expenses and identify opportunities to reduce what you pay.
Strategic renovations can actually lower your home insurance costs rather than raise them. Replacing your roof, updating your electrical system, installing a home security system, and investing in storm-resistant upgrades are all improvements that insurers tend to reward with lower premiums.
Certain dog breeds can raise your home insurance premium or lead to denied coverage in some locations. Breeds commonly flagged by insurers include pit bulls, rottweilers, German shepherds, Alaskan malamutes, and wolf-dog hybrids.
The materials your home is built from directly affect your insurance rate. Homes constructed from sturdier materials like concrete, brick, or stone typically cost less to insure than wood-framed homes, which carry greater exposure to pests, water damage, and fire.
A home worth $300,000 carries a higher annual premium than one valued at $170,000, and you can expect your payments to rise steadily as your home's value increases. A higher-value home costs more to insure because replacing or repairing it after a covered loss is more expensive.
Where you live is one of the most significant factors in your home insurance cost, with high-risk flood, hurricane, earthquake, wildfire, and tornado zones carrying higher premiums than mild climates.
Your distance from the nearest fire station and your neighborhood's crime rate also factor into what you pay. Because standard homeowners insurance typically excludes flood and earthquake coverage, some insurers sell these as separate policies, so if you live in a disaster-prone area, ask your provider about your options.
Older homes generally cost more to insure than newer ones because repairs tend to be more expensive and older construction often lacks modern safety features, with details like custom molding, wood floors, aluminum wiring, or outdated plumbing all increasing the likelihood of filing a claim. That said, renovations such as adding storm-proof windows or updating electrical systems can help older-home owners qualify for a lower rate.
Features like swimming pools, hot tubs, and treehouses are often classified as "attractive nuisances" by insurers, which can raise your premium because they increase the likelihood of injuries on your property. These same features can also drive up the cost of a claim if they need repair or replacement.
The age and condition of your roof can meaningfully affect your home insurance rate, since your roof is one of your home's primary defenses against weather damage. A roof that is 15 to 20 years old may result in higher premiums compared to a newer one.
Both your dwelling coverage amount and your liability coverage level affect your homeowners insurance premium. Add-on coverages such as sewer and drain back-up protection or an umbrella plan carry additional costs on top of your base policy.
Deductibles typically range from $500 to $2,000 or more, with lower deductibles generally resulting in higher annual premiums. Your deductible is the amount you pay out of pocket each time you file a claim, and it directly influences your premium.
A prior homeowners insurance claim on your record can push your rate higher, and living in an area with a high volume of claims, such as a region prone to natural disasters, can have the same effect even if you personally have never filed.
Your credit history can influence your home insurance rate, with a higher credit score typically translating to a lower premium. Note that some states prohibit insurers from using credit scores when setting prices, so this factor does not apply universally.
You may be able to get a discount on your homeowner's insurance for any number of reasons. Common discounts include:
Being an active military member, educator, or emergency responder
Being a non-smoker
Paying your premium annually instead of monthly
Having a monitored security system
Living in a gated community
Being a part of a homeowners association
Choosing paperless statements and billing
You can reduce your home insurance costs by taking a few steps. Here are the best ways to lower your home insurance cost:
Bundle your home and auto policies with one insurance company.
Shop around periodically for the best rates for your home.
Increase your deductible (if you have enough in savings to cover the cost should something happen).
Boost your credit score.
Make security and safety updates to your home, such as wind protection or a security alarm system.
Ask for discounts on your insurance policy.
Adjust your insurance coverage level and add-ons.
Avoid filing claims for small incidents that you can pay out of pocket.
Choose a homeowners insurance company by finding a company that provides coverage in your area, has competitive rates, offers discounts, and has good reviews. You should shop around and request price quotes from multiple companies before making a final decision.
Home insurance usually does not cover appliances that break down due to age or wear and tear, but covers repair or replacement cost under a covered incident. If you have a fire in your home and an appliance gets damaged, your home insurance is likely to cover the costs.
If you’re good people wanting to do business with good people, hire Matt. He is a consummate professional and utterly competent. He installed a water heater in my home at a price that beat competitors by hundreds of dollars with a promise to support the unit for its life (even after its 6 yr...
 Greene's Plumbing Services
This company does it right. Firstly, I want to say that Landan was a joy to work with. He was so kind, transparent, and had everything under control. His entire team showed up ready to work and they were all very respectful of the fact that we were in an office space. A little backstory – we...
 Krumlauf Floors
Great communication throughout from discussion of the project, and its options, to installation. They found a number of unforeseen challenges when mounting my TV and soundbar to, what was found as, an untraditional wall that didn’t allow for wires to be hidden behind the wall. The team was...
 Tether House
Professional and great to work with. Reliable, detail-oriented and knowledgeable. Will hire again in the future!
 P&P Painting, LLC
Custom Paint Jobs LLC took our exterior from drab to fab! We couldnt be happier.
 Custom Paint Jobs, LLC
The guys at PaveWay are top notch. From the estimate to the job being completed,all was done in a timely and professional manner. I myself was a DOT Engineer Inspector(know what to look for) and got to talking with Cameron and he himself was a Contract inspector for a few years,same job as...
 All Star Paving and Sealing
Before choosing a real estate agent, we conducted a lot of research to see who would be the best choice. Homes that Click stood out as the best Columbus has to offer: their rankings are excellent, their social media presence was strong, and I could tell they put a lot of work into their...
 Homes That Click Realtors
I have witnessed Mary Goodwin's knowledge, determination, and persistence in real estate and the way she professionally guides her clients throughout the home buying process. I am in the early stages of looking for a home, but already feel confident in the process with Mary leading the way.
 Ed Huck Team
Called Mark on a Thursday morning. Not really knowing if he could help me or not. I was having driveway, flooding issues due to a clogged channel drain and I was trying to figure out what direction to take. Heavy rains had come on Monday and again on Thursday leading to flooding in my garage...
 Mark Rodgers Construction
These guys are the real deal! Their pricing was definitely competitive and fair; nothing really to write home about. But when it came to attitude and installation they knocked it out of the park. I had 3 estimates and while one was similar $$ to Eco's, the can-do and professionalism Steve...
 Eco Glass Designs
From average costs to expert advice, get all the answers you need to get your job done.
When you buy a home, you’ll likely need hazard insurance to protect it from things like natural disasters and burglaries. Learn how insurance costs can vary.
If you’re not sure if you want moving insurance, you’re not alone. Most people don’t. This guide helps you learn the reasons you need or don’t need the coverage.
If a fire breaks out or a tree falls on your roof, homeowners insurance can protect you. This guide tells you everything you need to know about such policies.
Read these tips to get extra savings on your homeowners insurance policy premium with home security projects, improvements, and discount rates.
Asking yourself how much homeowners insurance you need can be daunting. Learn about coverages, options, and where to get answers to the question.
Does home insurance cover plumbing? It depends on the type of problem and how and why it occurred. Our guide covers all the nuances of this coverage.