Top-rated property appraisers.

Best property appraisers near Fulton, MO

Enter your zip and get matched with up to 5 pros

Need a pro for your property appraisal project in Fulton, MO?

Select your specific project to find the pro for you.

Top-Rated Property appraisers in Fulton - Updated Nov 2026

Property Appraiser FAQs, answered by experts

The differences between market value and appraised value depend on the local market, so they can match, or either one can be higher than the other. In a “seller’s market,” where there is an abundance of buyers, market value will likely sit higher than the appraised value because there’s more demand for the low inventory of homes. In a “buyer’s market,” where there are more homes than there are buyers, the market value is more likely to sit below the appraised value to entice buyers.

Depending on the size of the home, the appraisal itself can take several hours. After the appraiser’s visit is complete, it can take between a few days and a few weeks to get the report back. This timeline is largely dependent on the appraiser’s workload, research requirements, efficiency, and other factors.

The entire appraisal process takes from seven to 10 days. This timeline accounts for the many steps of the appraisal process, including the post-inspection report completed by the appraiser.

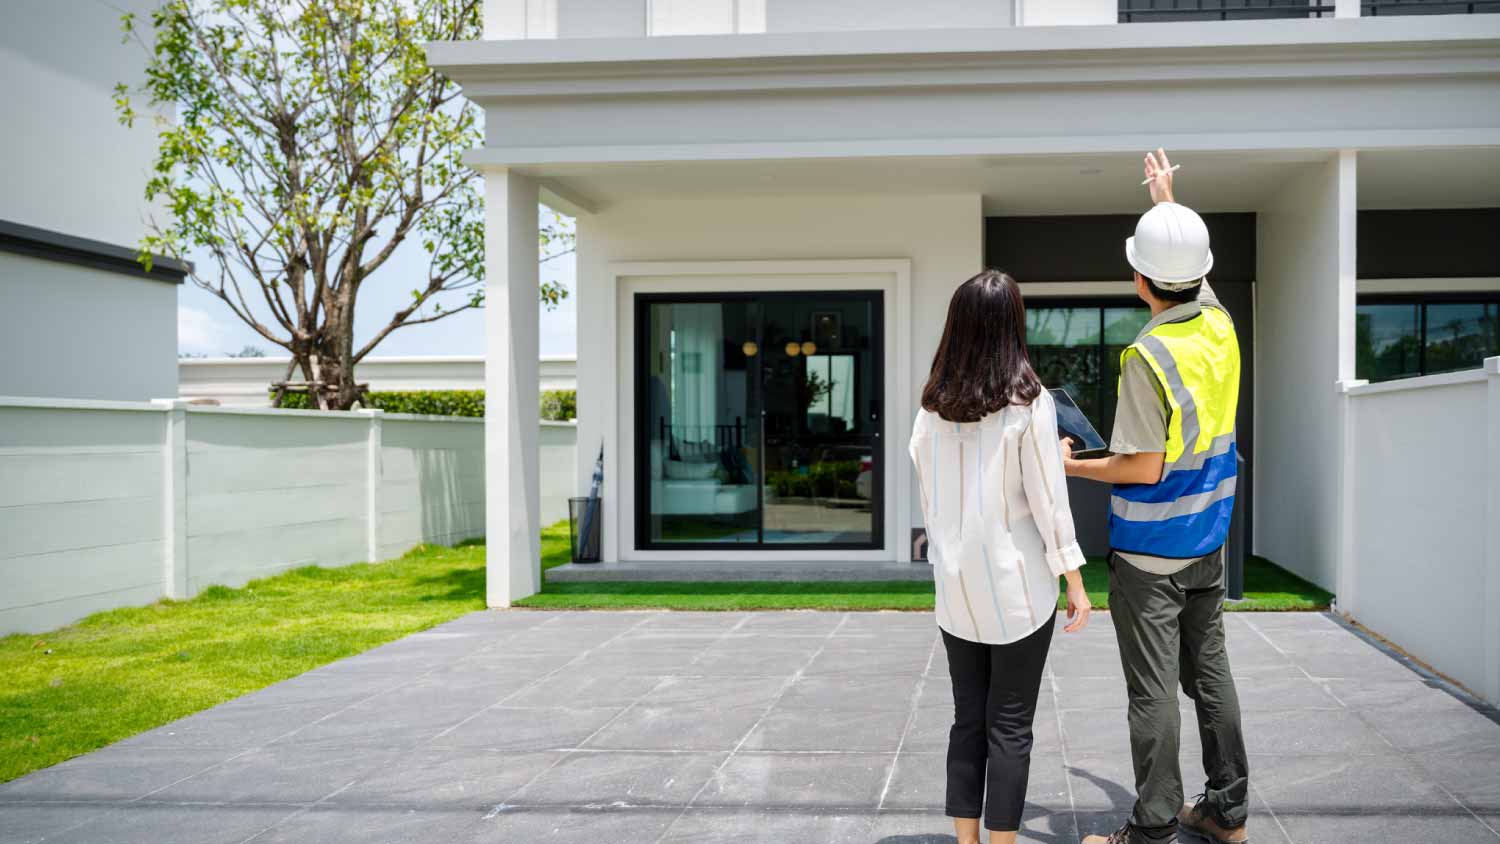
Home appraisal services include the following tasks:

  • Inspect home interior and exterior

  • Evaluate materials, features, fixtures, and renovations

  • Review comparable properties

  • Write an appraisal report

Ideally, you’d never pay more than the appraised value for a home, but there are some instances where it makes sense to do so. For example, if your current living arrangements are no longer viable and you need a place to move into quickly, paying more than the appraised value might be in your best interest to secure a new home. Additionally, if you’re buying in a hot market, overpaying for the home might be necessary to overcome the competition.

While there’s technically no limit to the dollar amount you can borrow for a home addition, the standard limit is around 80% of the value the addition is expected to add to your home. That means you could feasibly borrow up to $80,000 if an appraiser determines that the addition or bump out will add $100,000 in value to your property. You might also be limited by your debt-to-income ratio or credit score.

The Fulton, MO homeowners’ guide to property appraisals

From average costs to expert advice, get all the answers you need to get your job done.