"Hired to do valuation of a manufactured home - not on land. Gave appraisal comparison properties included land. therefore not an accurate valuation. Thought salesperson understood nuance."
Locally owned and operated real estate appraisal firm serving central and northeastern Illinois. We are experienced with all types of residential appraisals including single family units, 2-4 unit income properties, condominium, land appraisals, pre-listings, estate appraisals, bankruptcy and assessor related services, and more. Our priority is a high quality appraisal delivered in a quick turn around. Please call for availability outside of listed business hours.
" In the past, I was always a little wary of companies that made these kinds of offers - I didn't think that they could really do very much about property taxes.
But I was referred to Andrea Raila by my neighbor, so I thought I would give them a try.
I contacted them by phone and gave them the information about our property. They explained how the process worked, and sent forms out to me for signature. I signed the forms and sent them back and that was it. Upon receiving the reduction in taxes, I got a letter telling me the good news. We were very pleased with the outcome! We were also told that they felt that we could get a further reduction for the next year's taxes.
This company knows what they are doing and we will certainly use them in the future. All in all, this is a very professional organization and I would recommend their services to anyone."
The differences between market value and appraised value depend on the local market, so they can match, or either one can be higher than the other. In a “seller’s market,” where there is an abundance of buyers, market value will likely sit higher than the appraised value because there’s more demand for the low inventory of homes. In a “buyer’s market,” where there are more homes than there are buyers, the market value is more likely to sit below the appraised value to entice buyers.
Appraisals can come in above or below the list price or offer price for a property, and where it falls depends on many factors. Those include the condition of the property, the location, and the age of the home, but often, the condition of the market is the biggest determining factor. Where demand is high for properties, buyers compete with each other for homes, which tends to drive up offer prices above where appraisals come in. Where demand is low, you’ll often see the opposite happening.
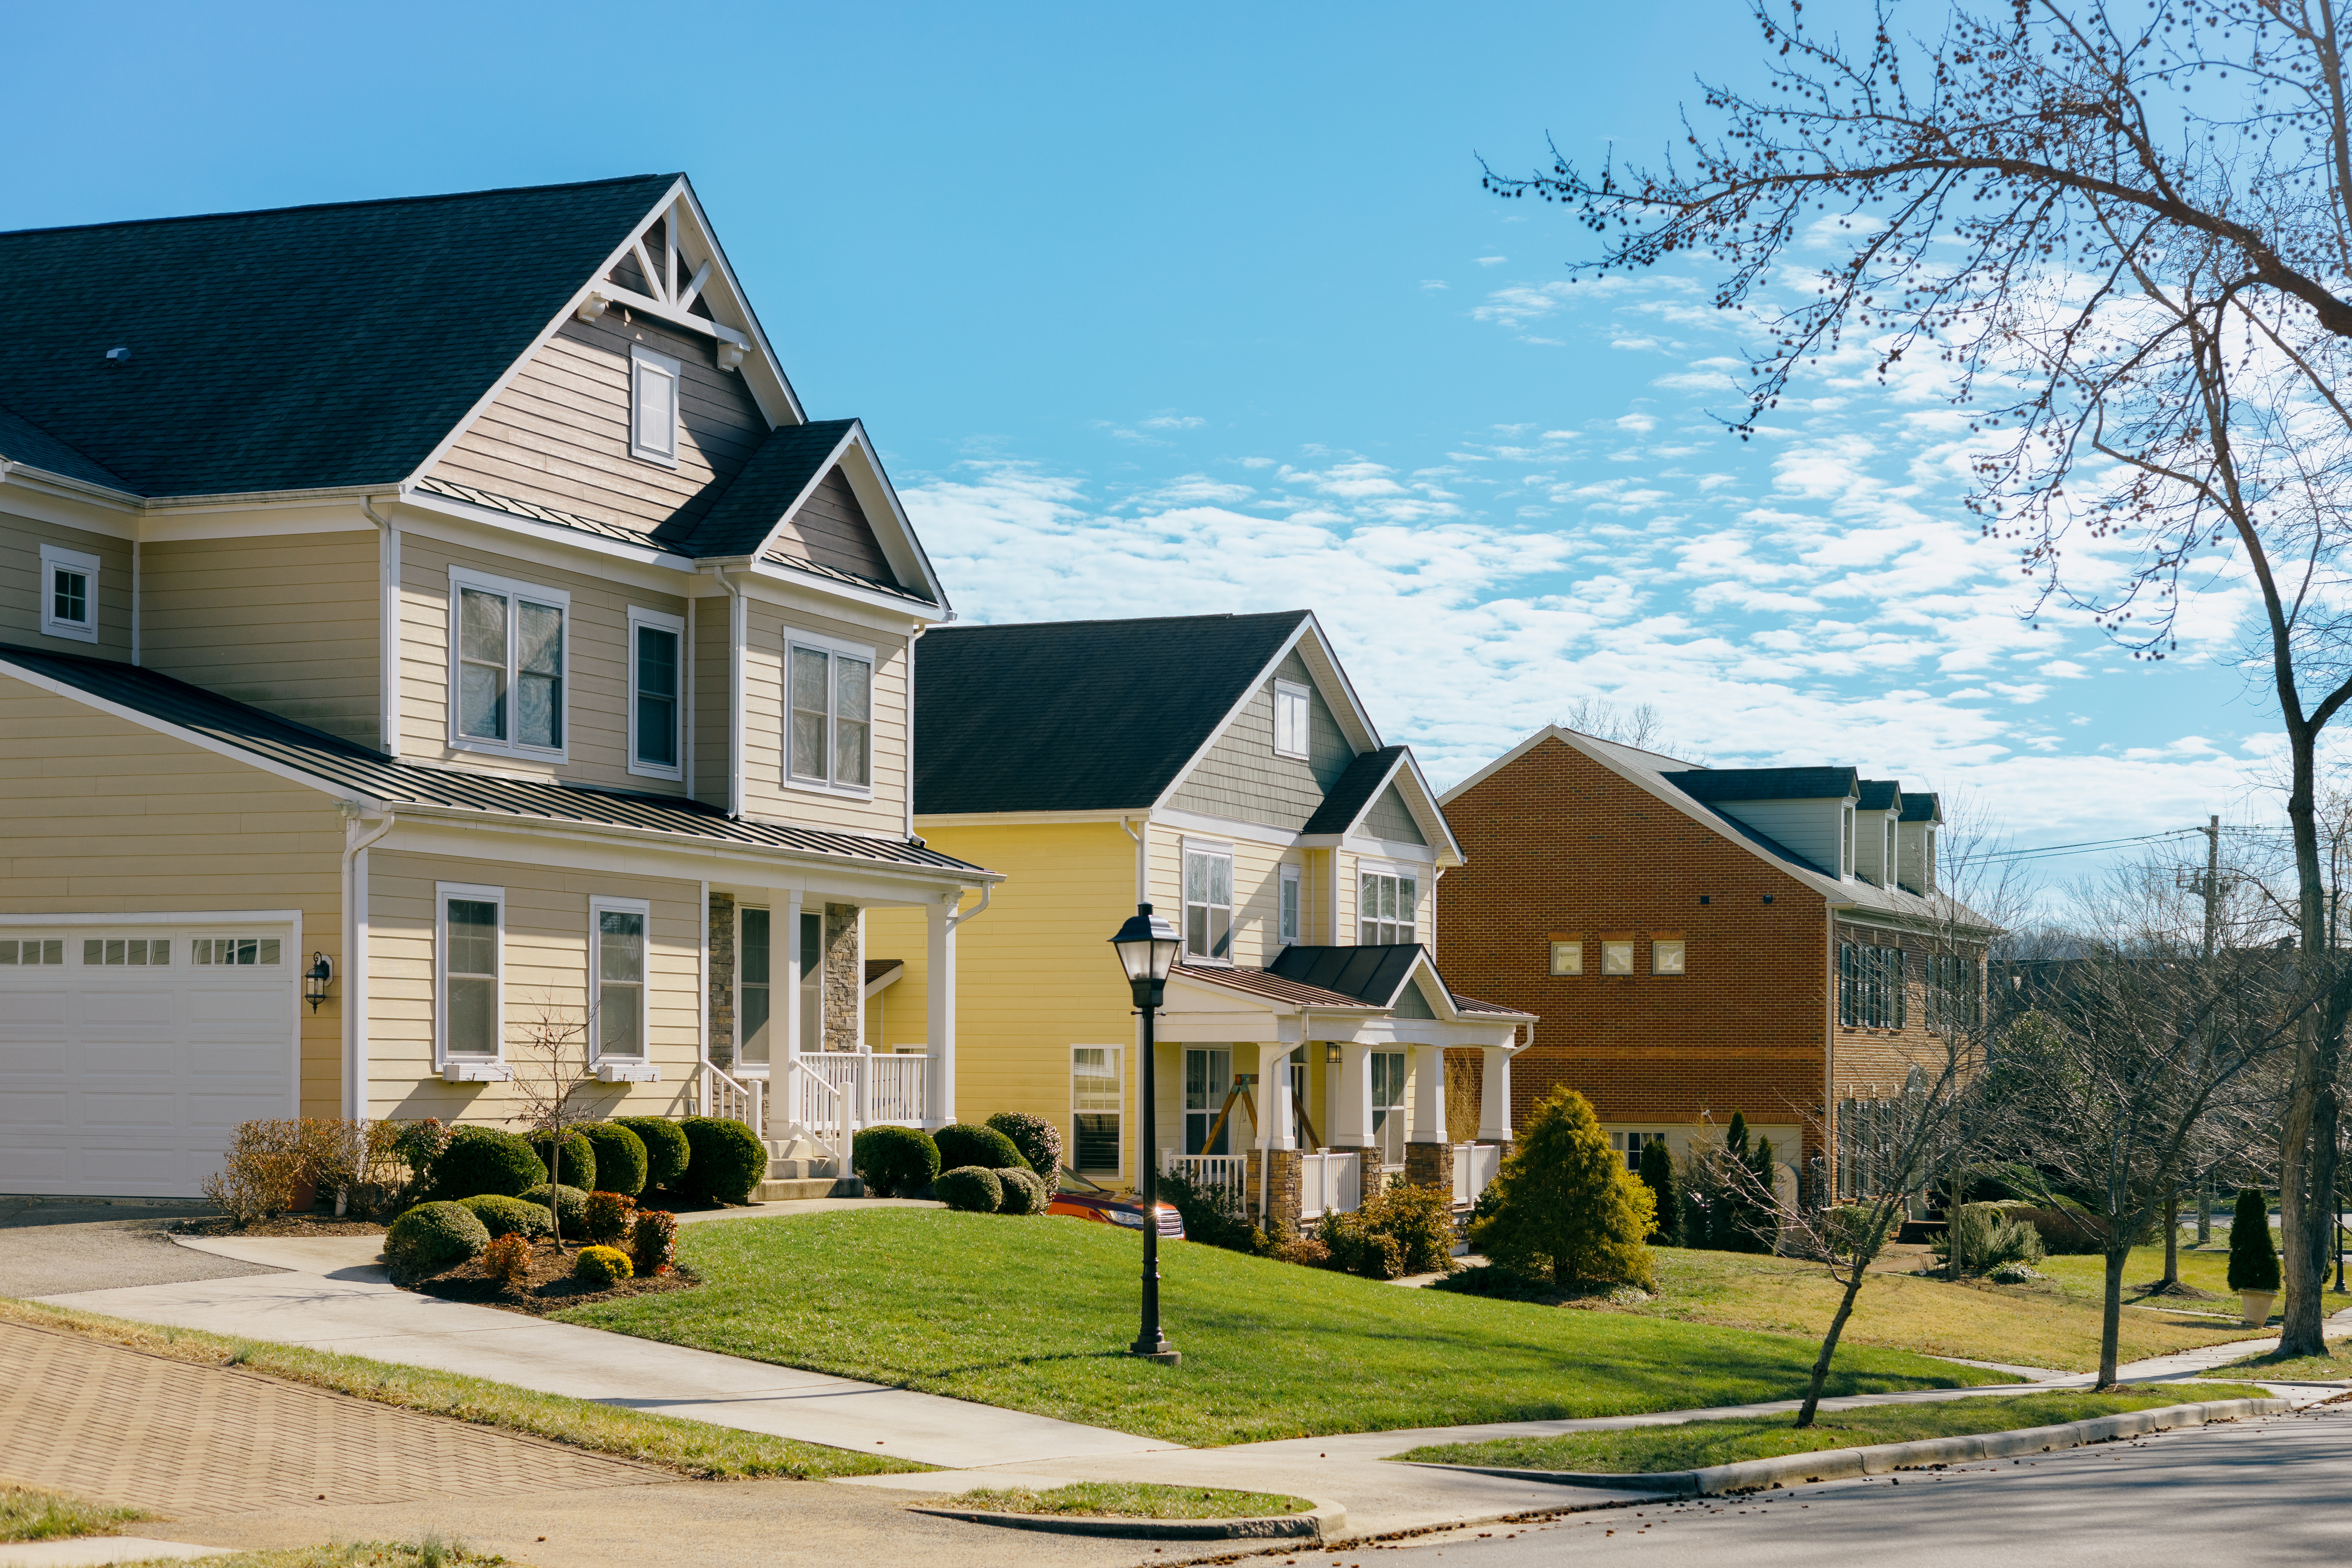
The condition and appearance of your yard can affect your home appraisal value. A well-maintained, attractive yard with curb appeal adds to a property’s value, while an overgrown, messy, poorly maintained yard can hurt your home’s appraisal. Even small cosmetic improvements to your yard, like adding mulch, trimming trees, and cleaning out plant beds, can help your appraisal value.
The cost to appraise a home depends on the type. Common types include:
Single-family homes: $300–$400
FHA or VA single-family homes: $400–$500
Condominium: $300–$500
Multi-family home: $500–$1,000
Apartment building: $1,500–$3,000
Commercial properties: $1,400–$10,000
Raw land: $1,000–$8,000
While some aspects of an appraisal, such as comparable properties nearby, are out of your control, there are several steps you can take to potentially increase your home's value. Make any necessary repairs and upgrades before the appraiser's visit, as they can only value what is currently part of the home, not its potential. Examples include renovating older areas, updating landscaping to boost curb appeal, and staging your home. You can also provide the appraiser with the cost of recent upgrades, which may increase your home's value by about 50% or more of what you paid for those improvements.
The Mendota, IL homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.