"Hired to do valuation of a manufactured home - not on land. Gave appraisal comparison properties included land. therefore not an accurate valuation. Thought salesperson understood nuance."
Ensures accurate valuation reflecting current market conditions, assisting in financial decisions.
While there’s technically no limit to the dollar amount you can borrow for a home addition, the standard limit is around 80% of the value the addition is expected to add to your home. That means you could feasibly borrow up to $80,000 if an appraiser determines that the addition or bump out will add $100,000 in value to your property. You might also be limited by your debt-to-income ratio or credit score.
Yes, experienced appraisers handle a variety of property types with tailored methods.
Both conventional loans and FHA loans are types of mortgages, but they have a few key differences. Conventional loans are backed by private lenders without any government backing, and FHA loans are guaranteed by a government agency. FHA loans are designed to be easier for borrowers with low credit scores or income to qualify for.
The entire appraisal process takes from seven to 10 days. This timeline accounts for the many steps of the appraisal process, including the post-inspection report completed by the appraiser.
Home appraisal services include the following tasks:
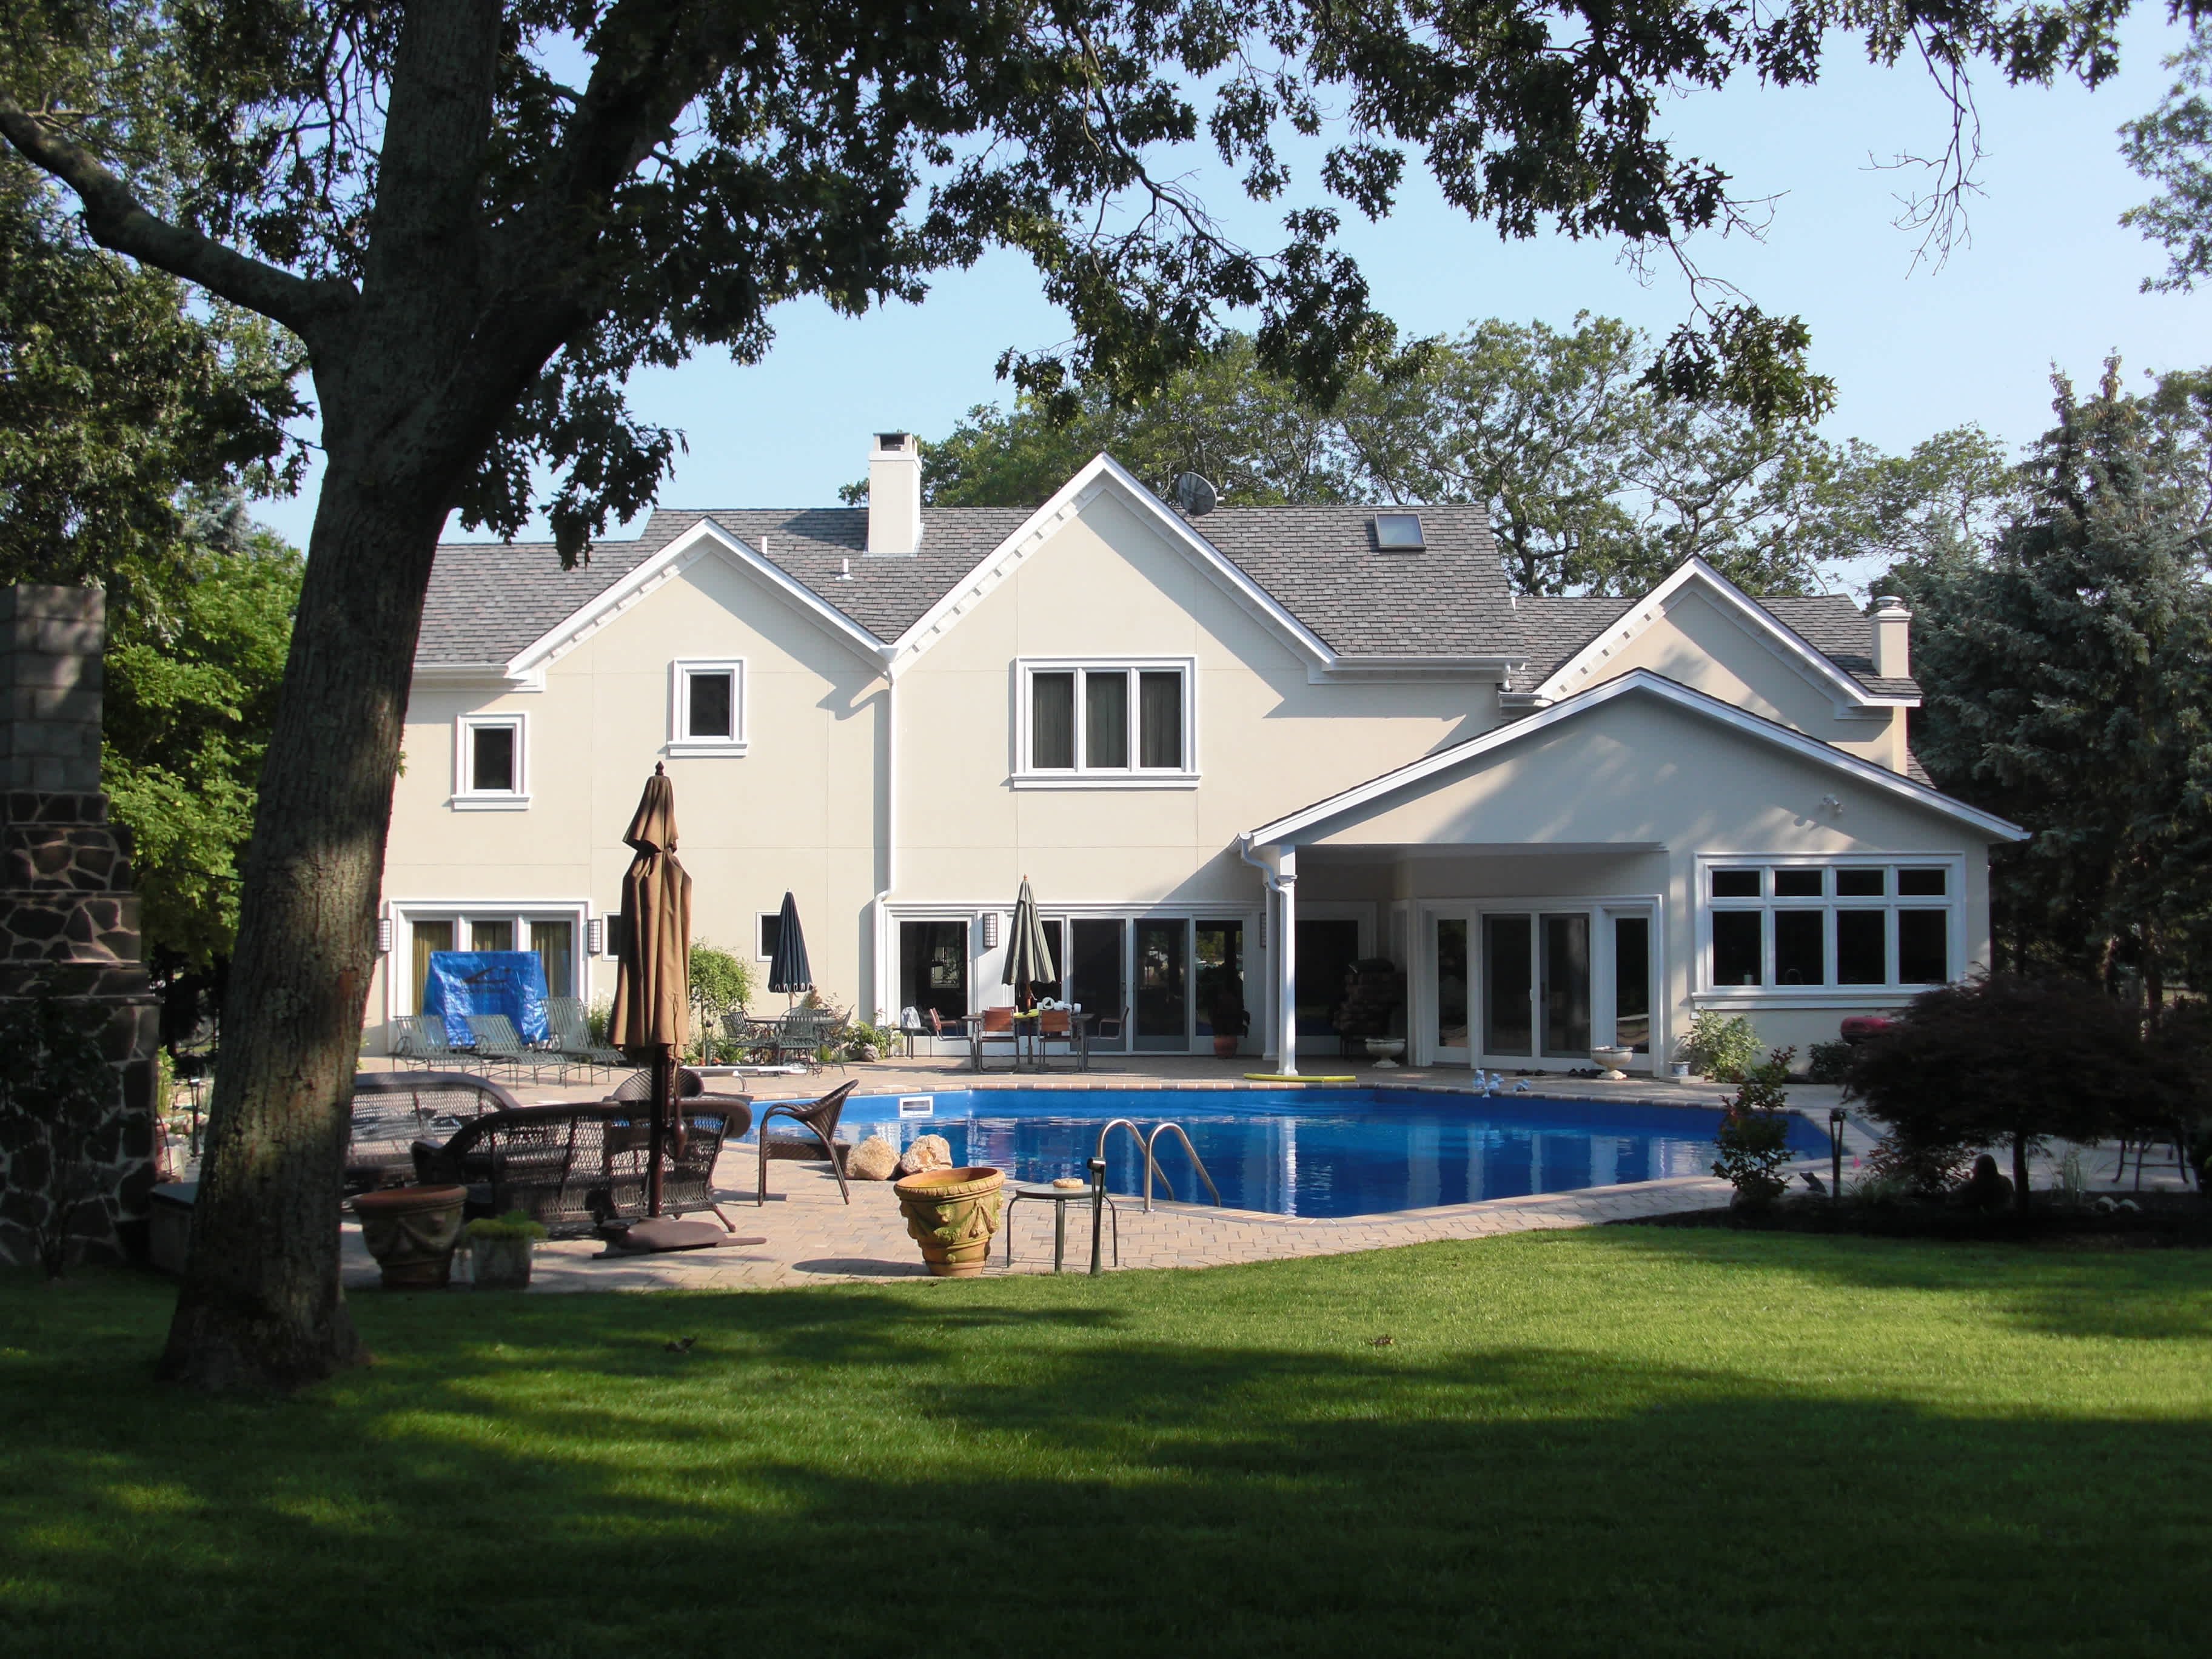
Inspect home interior and exterior
Evaluate materials, features, fixtures, and renovations
Review comparable properties
Write an appraisal report
The Hoven, SD homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.