"Hired to do valuation of a manufactured home - not on land. Gave appraisal comparison properties included land. therefore not an accurate valuation. Thought salesperson understood nuance."
We pride our company on reliability, great communication, integrity, and quality work. We are experts in our trade and will do our best to keep you as educated as we can on your particular task or project. We look forward to earning your business!
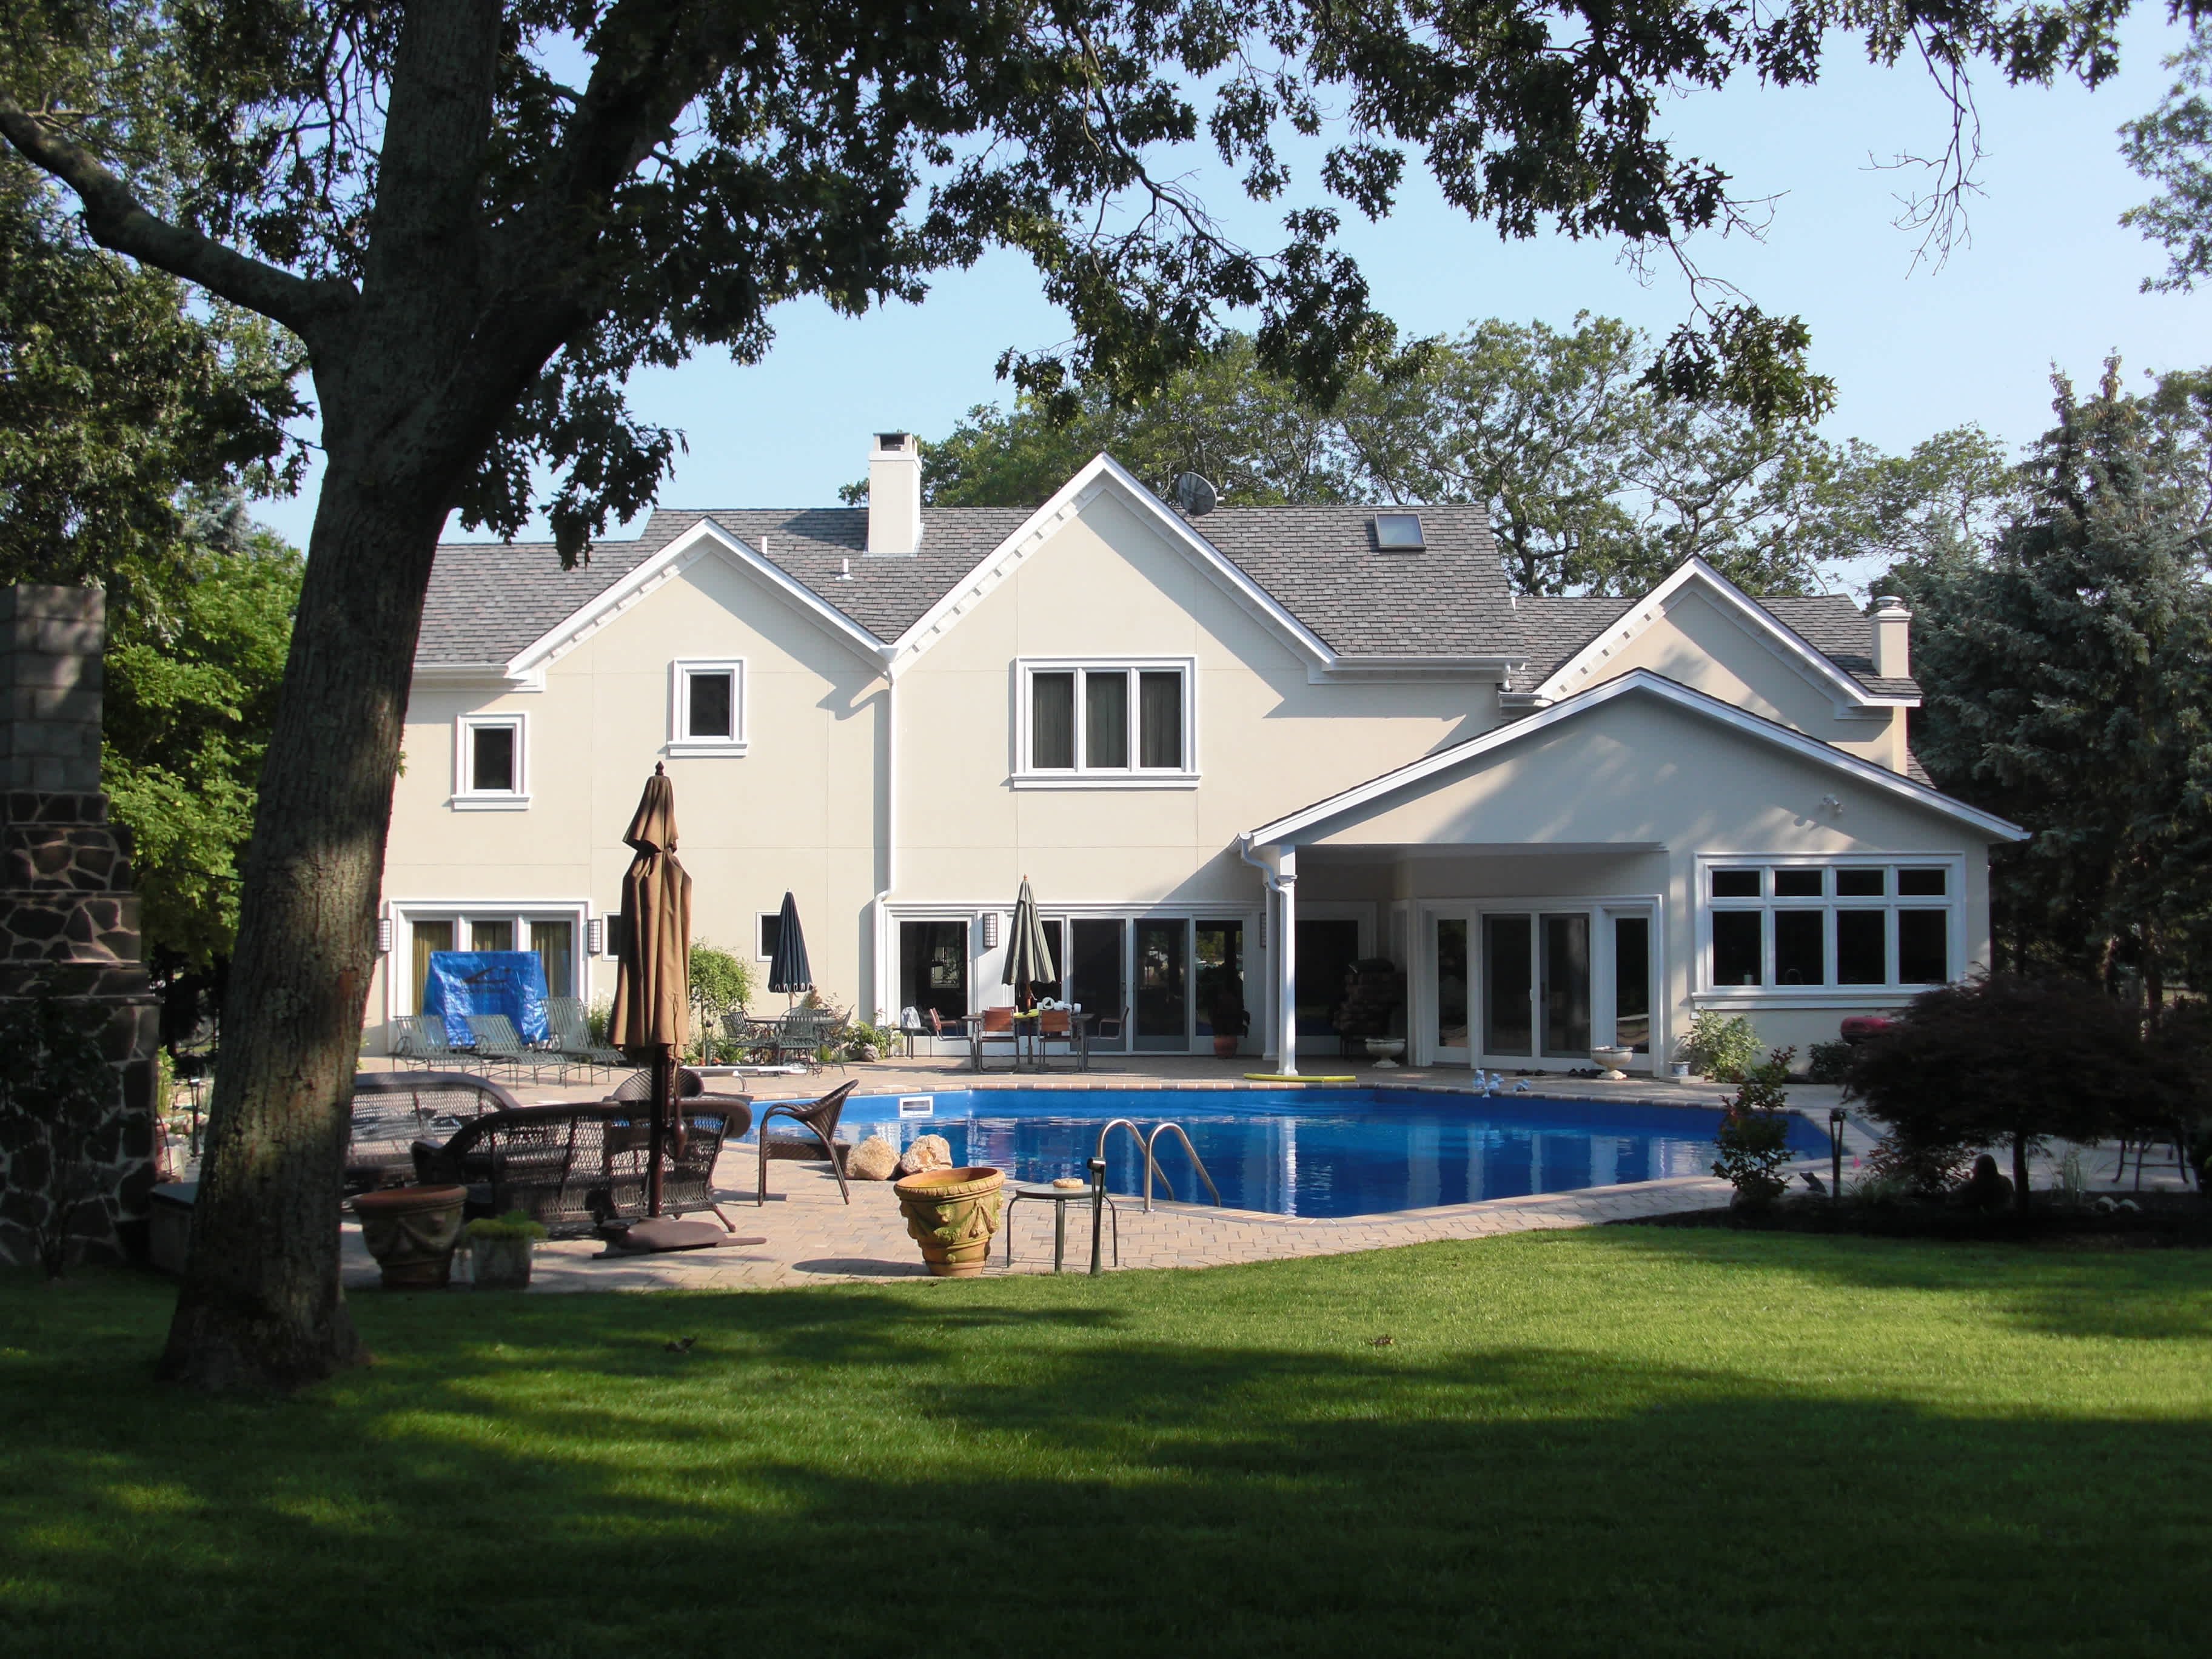
The condition and appearance of your yard can affect your home appraisal value. A well-maintained, attractive yard with curb appeal adds to a property’s value, while an overgrown, messy, poorly maintained yard can hurt your home’s appraisal. Even small cosmetic improvements to your yard, like adding mulch, trimming trees, and cleaning out plant beds, can help your appraisal value.
An FHA appraisal is valid for 180 days from the effective date of the report. In some cases, you can have the appraisal recertified if you make your request before the original expires so that you still may obtain an FHA loan. If approved, your appraisal update is valid for one year.
The cost to appraise a home depends on the type. Common types include:
Single-family homes: $300–$400
FHA or VA single-family homes: $400–$500
Condominium: $300–$500
Multi-family home: $500–$1,000
Apartment building: $1,500–$3,000
Commercial properties: $1,400–$10,000
Raw land: $1,000–$8,000
In most cases, you can expect home automation to boost your home value. This technology makes the homeowner’s life easier and more comfortable, and some provide increased safety and protection. Buyers will likely recognize value in security systems and utility monitors, as well as comfort-focused upgrades that save on electric bills while keeping interior rooms at the desired temperature and humidity. On average, you can expect a 50% and 75% return on investment on home automation services, and potentially even more if the automation reduces homeowner’s insurance.
Both conventional loans and FHA loans are types of mortgages, but they have a few key differences. Conventional loans are backed by private lenders without any government backing, and FHA loans are guaranteed by a government agency. FHA loans are designed to be easier for borrowers with low credit scores or income to qualify for.
The Leola, SD homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.