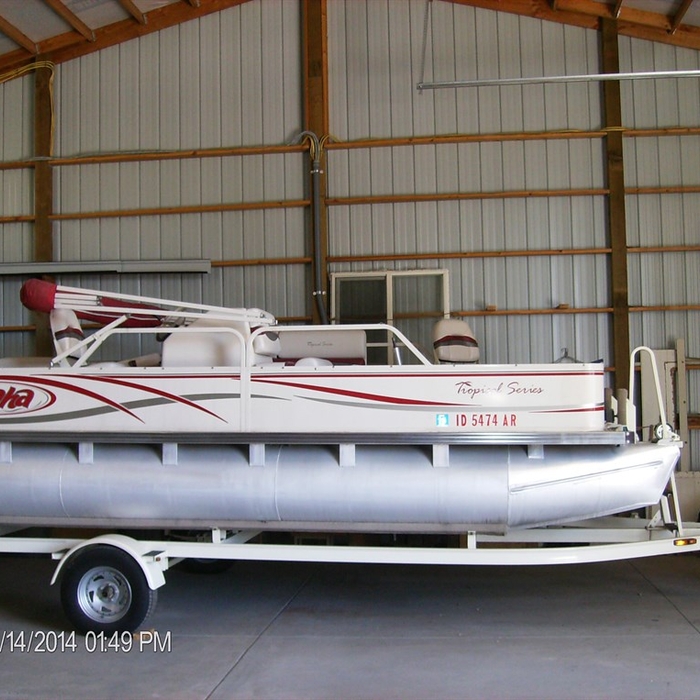
I can appraise anything that moves or can be moved. I can travel short or long distances,\n I have never been 2nd guessed or questioned on an appraisal. I have been doing appraisals\n for 12yrs. I can appraise at you location or I have done them at auctions or at business locations.\n Everyone that has purchased my services have been very satisfied and have told friends and \n neighbors about me. I do time wise appraisals but thorough, prices for appraisals is based on item or items to be appraised I am very efficient and thorough. I ask for a small % up front (good faith money by the client) and the rest when appraisal is complete and the client is satisfied with the results or payments can be worked out before appraisal is started as agreed to by both parties.\n I am available 24/7 by cell or landline phone or e-mail.
Both conventional loans and FHA loans are types of mortgages, but they have a few key differences. Conventional loans are backed by private lenders without any government backing, and FHA loans are guaranteed by a government agency. FHA loans are designed to be easier for borrowers with low credit scores or income to qualify for.
While some aspects of an appraisal, such as comparable properties nearby, are out of your control, there are several steps you can take to potentially increase your home's value. Make any necessary repairs and upgrades before the appraiser's visit, as they can only value what is currently part of the home, not its potential. Examples include renovating older areas, updating landscaping to boost curb appeal, and staging your home. You can also provide the appraiser with the cost of recent upgrades, which may increase your home's value by about 50% or more of what you paid for those improvements.
An FHA appraisal is valid for 180 days from the effective date of the report. In some cases, you can have the appraisal recertified if you make your request before the original expires so that you still may obtain an FHA loan. If approved, your appraisal update is valid for one year.
Yes, awnings can add value to a home, primarily by boosting its curb appeal and providing more usable outdoor space. While the exact monetary return on investment depends on the awning's size, style, and quality, they offer an excellent appeal factor to potential buyers. For example, an awning with a trendy metal roof can be particularly attractive. Even if the direct increase in resale value is modest, a well-chosen awning enhances the home's functionality and aesthetic.
The differences between market value and appraised value depend on the local market, so they can match, or either one can be higher than the other. In a “seller’s market,” where there is an abundance of buyers, market value will likely sit higher than the appraised value because there’s more demand for the low inventory of homes. In a “buyer’s market,” where there are more homes than there are buyers, the market value is more likely to sit below the appraised value to entice buyers.
The Busby, MT homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.