I can appraise anything that moves or can be moved. I can travel short or long distances,\n I have never been 2nd guessed or questioned on an appraisal. I have been doing appraisals\n for 12yrs. I can appraise at you location or I have done them at auctions or at business locations.\n Everyone that has purchased my services have been very satisfied and have told friends and \n neighbors about me. I do time wise appraisals but thorough, prices for appraisals is based on item or items to be appraised I am very efficient and thorough. I ask for a small % up front (good faith money by the client) and the rest when appraisal is complete and the client is satisfied with the results or payments can be worked out before appraisal is started as agreed to by both parties.\n I am available 24/7 by cell or landline phone or e-mail.
We pride our company on reliability, great communication, integrity, and quality work. We are experts in our trade and will do our best to keep you as educated as we can on your particular task or project. We look forward to earning your business! Book with us online or feel free to give us a call today!
Both conventional loans and FHA loans are types of mortgages, but they have a few key differences. Conventional loans are backed by private lenders without any government backing, and FHA loans are guaranteed by a government agency. FHA loans are designed to be easier for borrowers with low credit scores or income to qualify for.
Foundation cracks won’t always affect your appraised value. All foundations crack due to normal settlement, so hairline cracks that aren’t leaking or uneven from side to side are unlikely to have an impact on your appraisal. Structural cracks, on the other hand, often lead to a reduced appraised value, especially if the underlying problem will cause the issue to worsen over time.
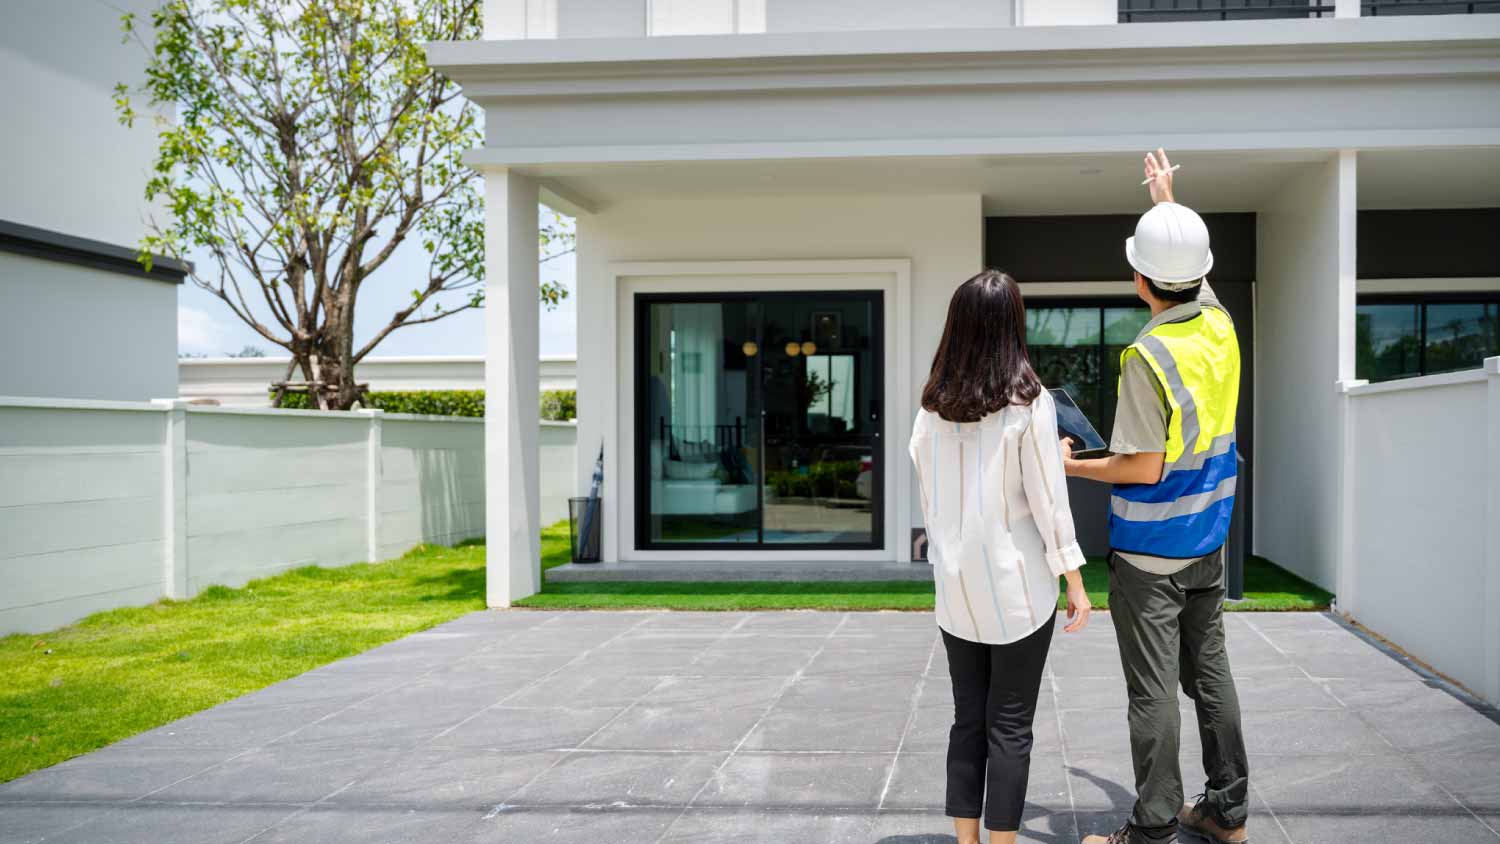
While some aspects of an appraisal, such as comparable properties nearby, are out of your control, there are several steps you can take to potentially increase your home's value. Make any necessary repairs and upgrades before the appraiser's visit, as they can only value what is currently part of the home, not its potential. Examples include renovating older areas, updating landscaping to boost curb appeal, and staging your home. You can also provide the appraiser with the cost of recent upgrades, which may increase your home's value by about 50% or more of what you paid for those improvements.
Xeriscaping can absolutely increase your home value, but the return on investment (ROI) depends on where you live and how prevalent xeriscaping is in your area. In drought-prone climates, xeriscaping can boost your curb appeal and make your home more appealing to buyers due to the reduced maintenance and watering costs. However, in areas where xeriscaping isn’t the norm, some buyers may be willing to pay less for a xeriscaped property if they don’t like the appearance.
In most cases, installing a tennis court on your property will drive up your property taxes. Property taxes are determined, in part, based on improvements made to your property, which includes anything with a permanent foundation. Since most home tennis courts include a large concrete foundation, your property taxes will likely increase following the installation. A general rule of thumb is that if your project requires permits—like for a foundation or fencing for a tennis court—then your property taxes will be affected.
The Mackay, ID homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.