"Hired to do valuation of a manufactured home - not on land. Gave appraisal comparison properties included land. therefore not an accurate valuation. Thought salesperson understood nuance."
Home Base Appraisal Management was founded in May 2009. We started our company with high hopes in the front room of the owner's home. We took everything one step at a time and have achieved more than we ever thought we would. After 6 years in business we have grown out of the basement and have become one of Inc 5000's fastest growing companies in America. Home Base has a reputation of outstanding communications, and customer service. We have one of the nations largest networks of appraisers, and provide appraisal services in the majority of the United States. Please call us today to book your appointment!
The purpose of the home appraisal determines which party pays for it. You’re generally responsible for the cost if you need to know the current value of your home to refinance your mortgage, though in some instances the lender will pay for it. The buyer pays for the appraisal when they are applying for their mortgage.
Land doesn’t depreciate in the same way that a house, vehicle, or other property does, but it can lose value based on various factors. Environmental changes, nearby development, zoning changes, and economic downturns can all cause land to lose value over time. Value is a comparative figure, so as other related factors change, so can land’s value.
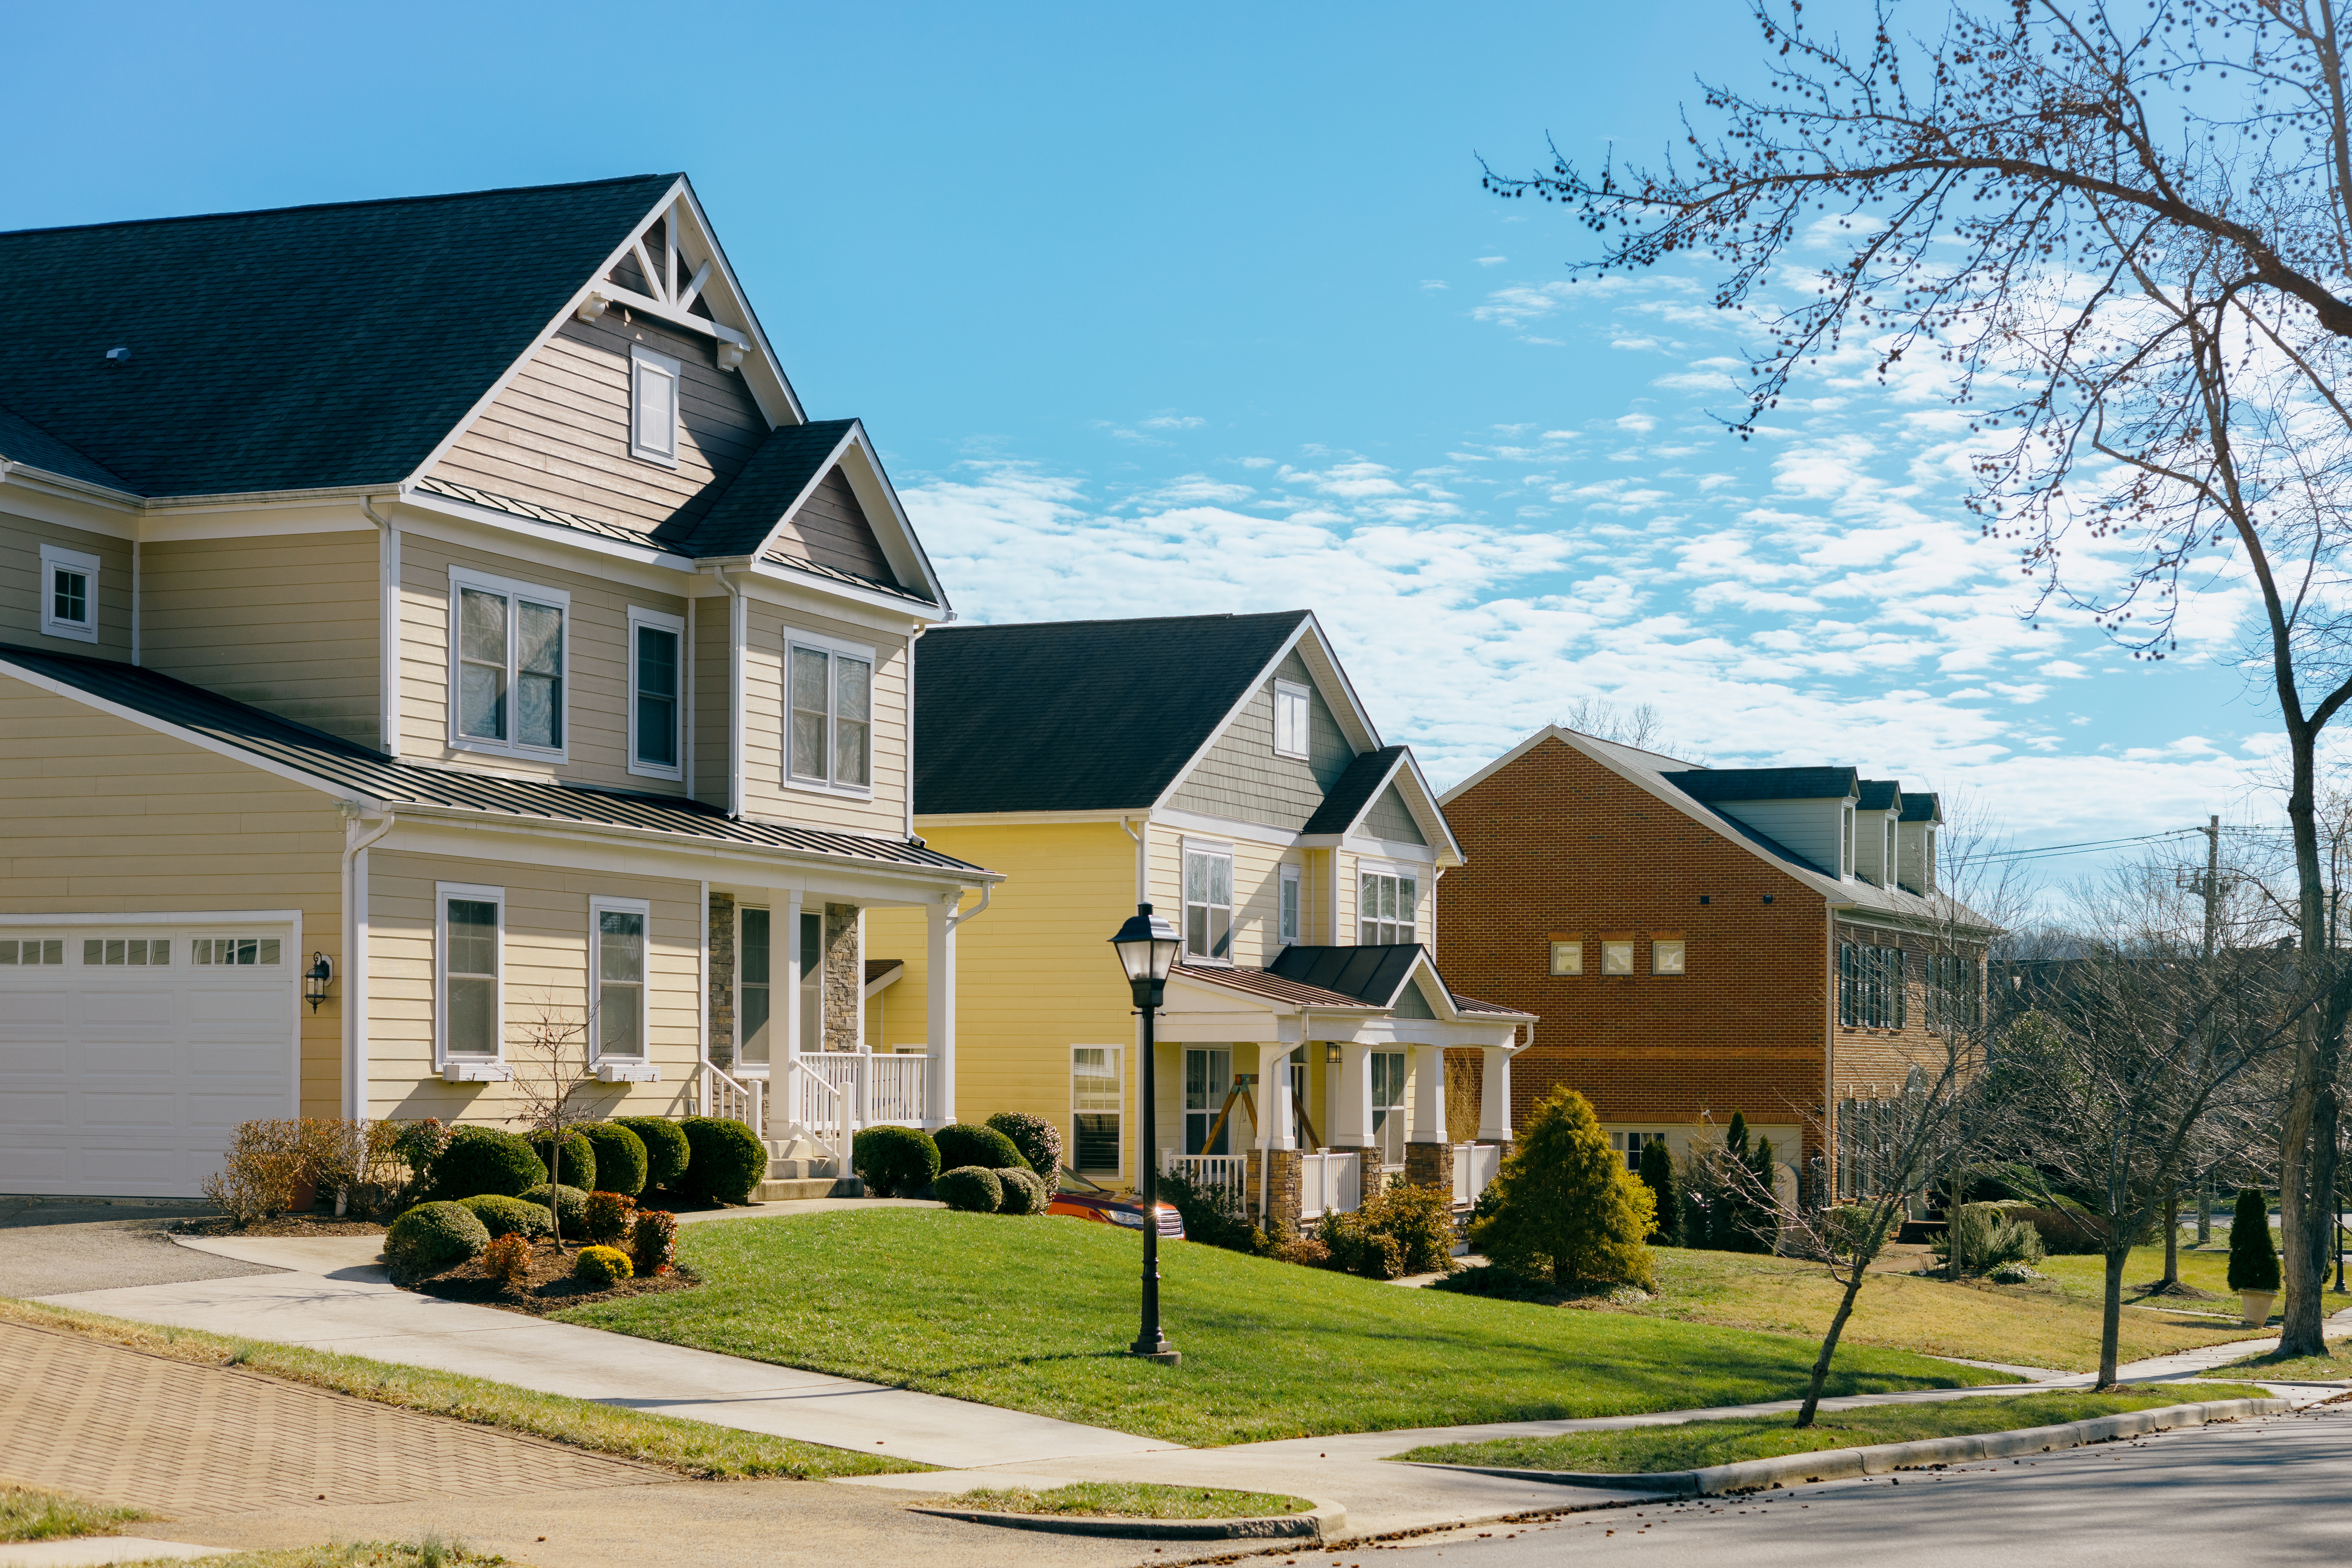
The condition and appearance of your yard can affect your home appraisal value. A well-maintained, attractive yard with curb appeal adds to a property’s value, while an overgrown, messy, poorly maintained yard can hurt your home’s appraisal. Even small cosmetic improvements to your yard, like adding mulch, trimming trees, and cleaning out plant beds, can help your appraisal value.
A property valuation, sometimes called a comparative market analysis or CMA, provides a real estate expert’s opinion on how much your property will sell for. It takes many things into consideration, like the condition and location of the home, but ultimately, all that matters for a property valuation is what a buyer might be willing to pay for the property. An appraisal is more concerned with determining the value. A valuation is to estimate what you’ll get for a property, while an appraisal helps a lender establish loan-to-value ratios and loan amounts.
Your home insurance company may allow you to use an appraisal instead of an inspection when you apply for coverage. Keep in mind that despite this, an appraisal is far less detailed than the different types of home inspections available and may not reveal potential risks that you’ll want to know about.
The Halls Crossing, UT homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.