"Hired to do valuation of a manufactured home - not on land. Gave appraisal comparison properties included land. therefore not an accurate valuation. Thought salesperson understood nuance."
"Stewart appraiser is a reliable professional company, both of them, David and Harriet. I only wish, they modernizes their communication and bank accounts to make it faster."
In most cases, installing a tennis court on your property will drive up your property taxes. Property taxes are determined, in part, based on improvements made to your property, which includes anything with a permanent foundation. Since most home tennis courts include a large concrete foundation, your property taxes will likely increase following the installation. A general rule of thumb is that if your project requires permits—like for a foundation or fencing for a tennis court—then your property taxes will be affected.
Yes, home appraisers look at your windows when appraising your property to determine the market value of your home. They’ll factor in the type of windows, quality, condition, whether or not there are screens covering the windows, frame materials, size, insulation, and more to come up with an unbiased property assessment.
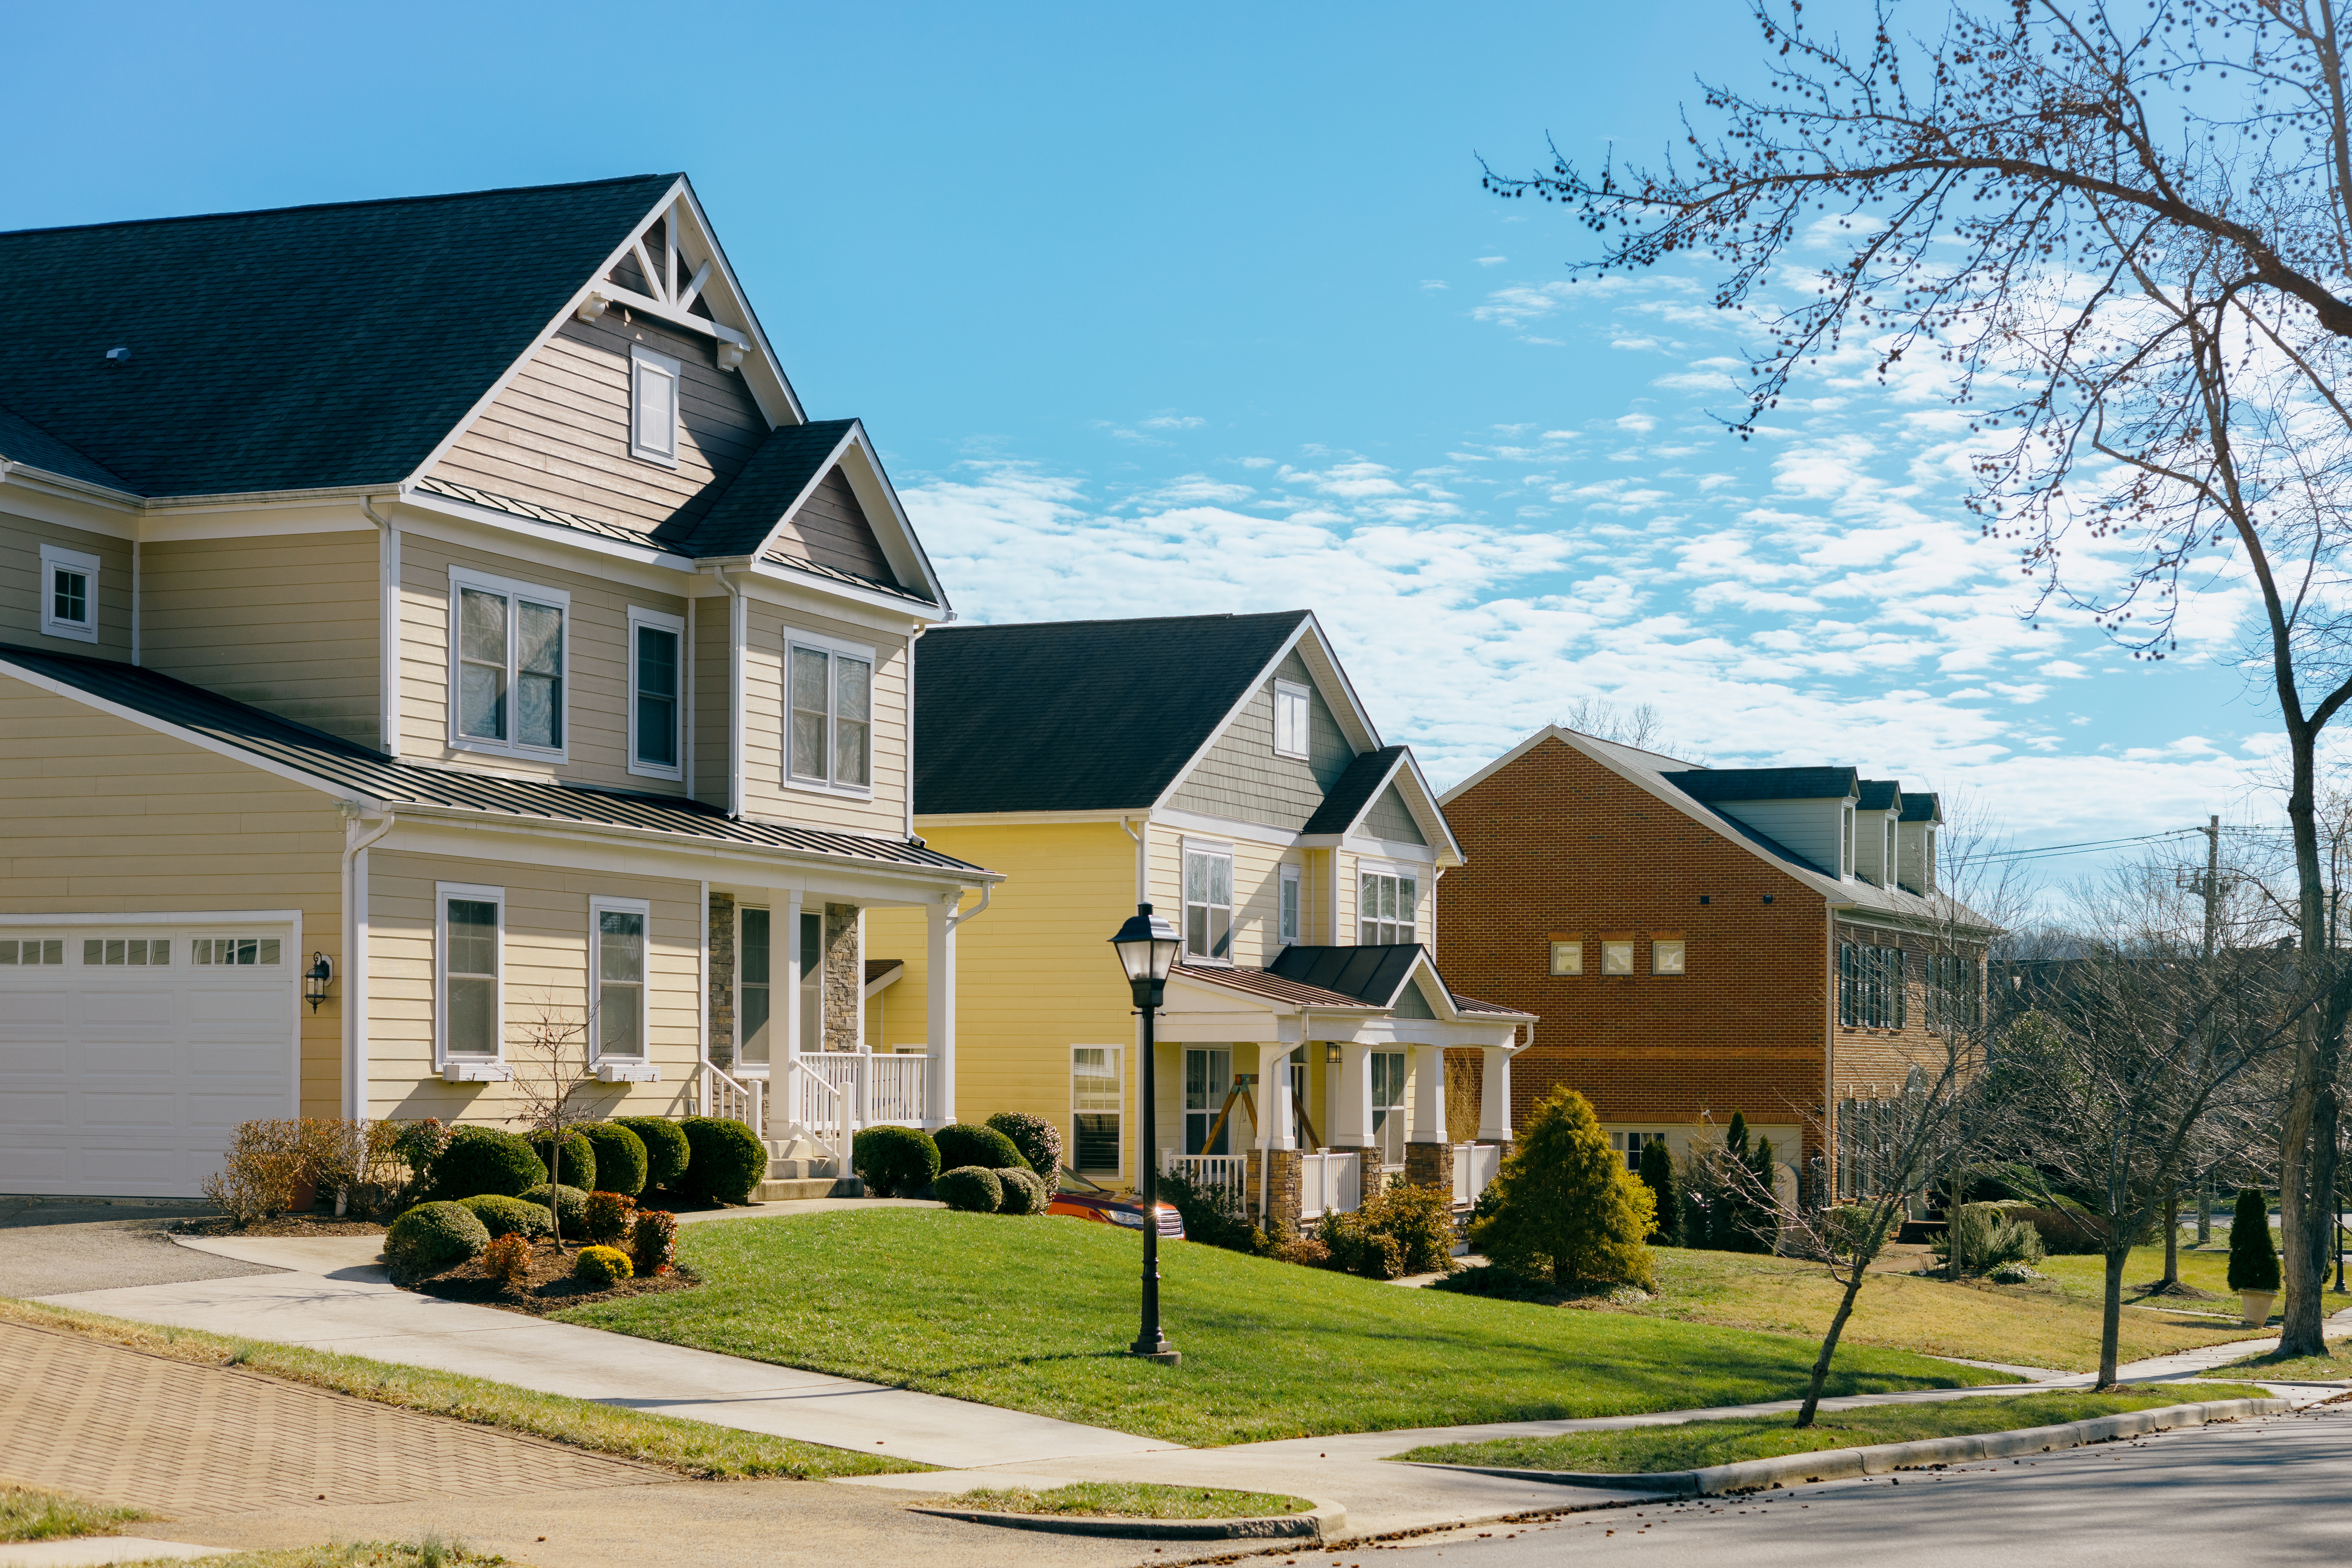
The condition and appearance of your yard can affect your home appraisal value. A well-maintained, attractive yard with curb appeal adds to a property’s value, while an overgrown, messy, poorly maintained yard can hurt your home’s appraisal. Even small cosmetic improvements to your yard, like adding mulch, trimming trees, and cleaning out plant beds, can help your appraisal value.
The differences between market value and appraised value depend on the local market, so they can match, or either one can be higher than the other. In a “seller’s market,” where there is an abundance of buyers, market value will likely sit higher than the appraised value because there’s more demand for the low inventory of homes. In a “buyer’s market,” where there are more homes than there are buyers, the market value is more likely to sit below the appraised value to entice buyers.
While there’s technically no limit to the dollar amount you can borrow for a home addition, the standard limit is around 80% of the value the addition is expected to add to your home. That means you could feasibly borrow up to $80,000 if an appraiser determines that the addition or bump out will add $100,000 in value to your property. You might also be limited by your debt-to-income ratio or credit score.
The Saltillo, TN homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.