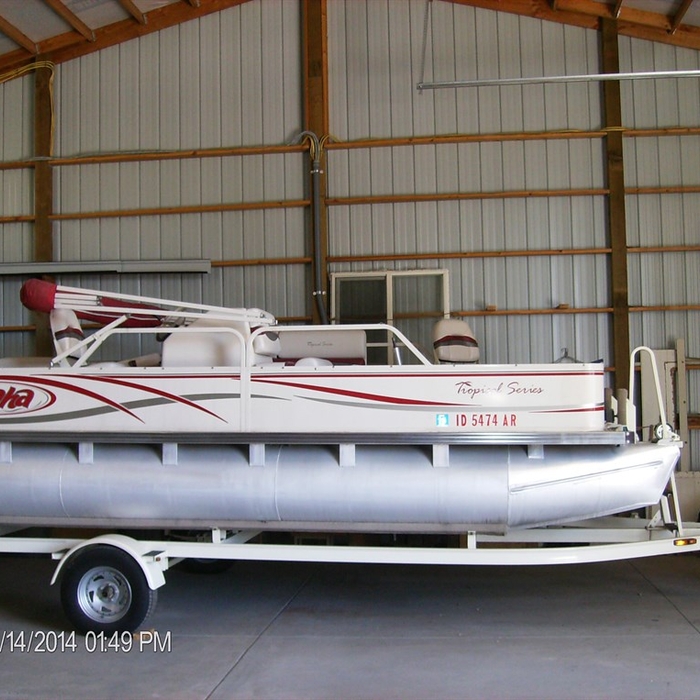
I can appraise anything that moves or can be moved. I can travel short or long distances,\n I have never been 2nd guessed or questioned on an appraisal. I have been doing appraisals\n for 12yrs. I can appraise at you location or I have done them at auctions or at business locations.\n Everyone that has purchased my services have been very satisfied and have told friends and \n neighbors about me. I do time wise appraisals but thorough, prices for appraisals is based on item or items to be appraised I am very efficient and thorough. I ask for a small % up front (good faith money by the client) and the rest when appraisal is complete and the client is satisfied with the results or payments can be worked out before appraisal is started as agreed to by both parties.\n I am available 24/7 by cell or landline phone or e-mail.
Ideally, you’d never pay more than the appraised value for a home, but there are some instances where it makes sense to do so. For example, if your current living arrangements are no longer viable and you need a place to move into quickly, paying more than the appraised value might be in your best interest to secure a new home. Additionally, if you’re buying in a hot market, overpaying for the home might be necessary to overcome the competition.
The cost to appraise a home depends on the type. Common types include:
Single-family homes: $300–$400
FHA or VA single-family homes: $400–$500
Condominium: $300–$500
Multi-family home: $500–$1,000
Apartment building: $1,500–$3,000
Commercial properties: $1,400–$10,000
Raw land: $1,000–$8,000
An FHA appraisal is valid for 180 days from the effective date of the report. In some cases, you can have the appraisal recertified if you make your request before the original expires so that you still may obtain an FHA loan. If approved, your appraisal update is valid for one year.
As a seller, it might feel tempting to skip the appraisal, especially in a hot market that sees a lot of all-cash offers. While you can technically forgo it and hope for an all-cash offer, you’ll likely have a very tough time selling without an appraisal.
In addition to protecting lenders from risk, appraisals also protect buyers’ investments. As such, it isn’t typically recommended for buyers to skip appraisals.
Whether or not new windows increase property taxes depends on where you live and by how much your upgrade increases your home’s value. Smaller projects likely won’t result in increased property taxes, but it’s always a good idea to err on the side of caution and check. Contact your local county appraisal department for the most accurate information about property taxes in your area.
The Malta, MT homeowners’ guide to property appraisals
From average costs to expert advice, get all the answers you need to get your job done.
Home appraisals are an important part of buying or selling a home and getting a mortgage loan. Learn more about home appraisal costs and what they include.
FHA loans are backed by the government and come with specific FHA appraisal guidelines and requirements. Learn what an FHA appraisal entails in this guide.